Lawmakers Demand Explanation on SBA's Policy Reduction Affecting Small Business Lending by 46%
A dramatic reduction in small business lending has sparked concern among lawmakers and entrepreneurs alike, following the implementation of new Small Business Administration (SBA) policies in 2025. These changes, which include stricter citizenship verification rules and heightened lending requiremen
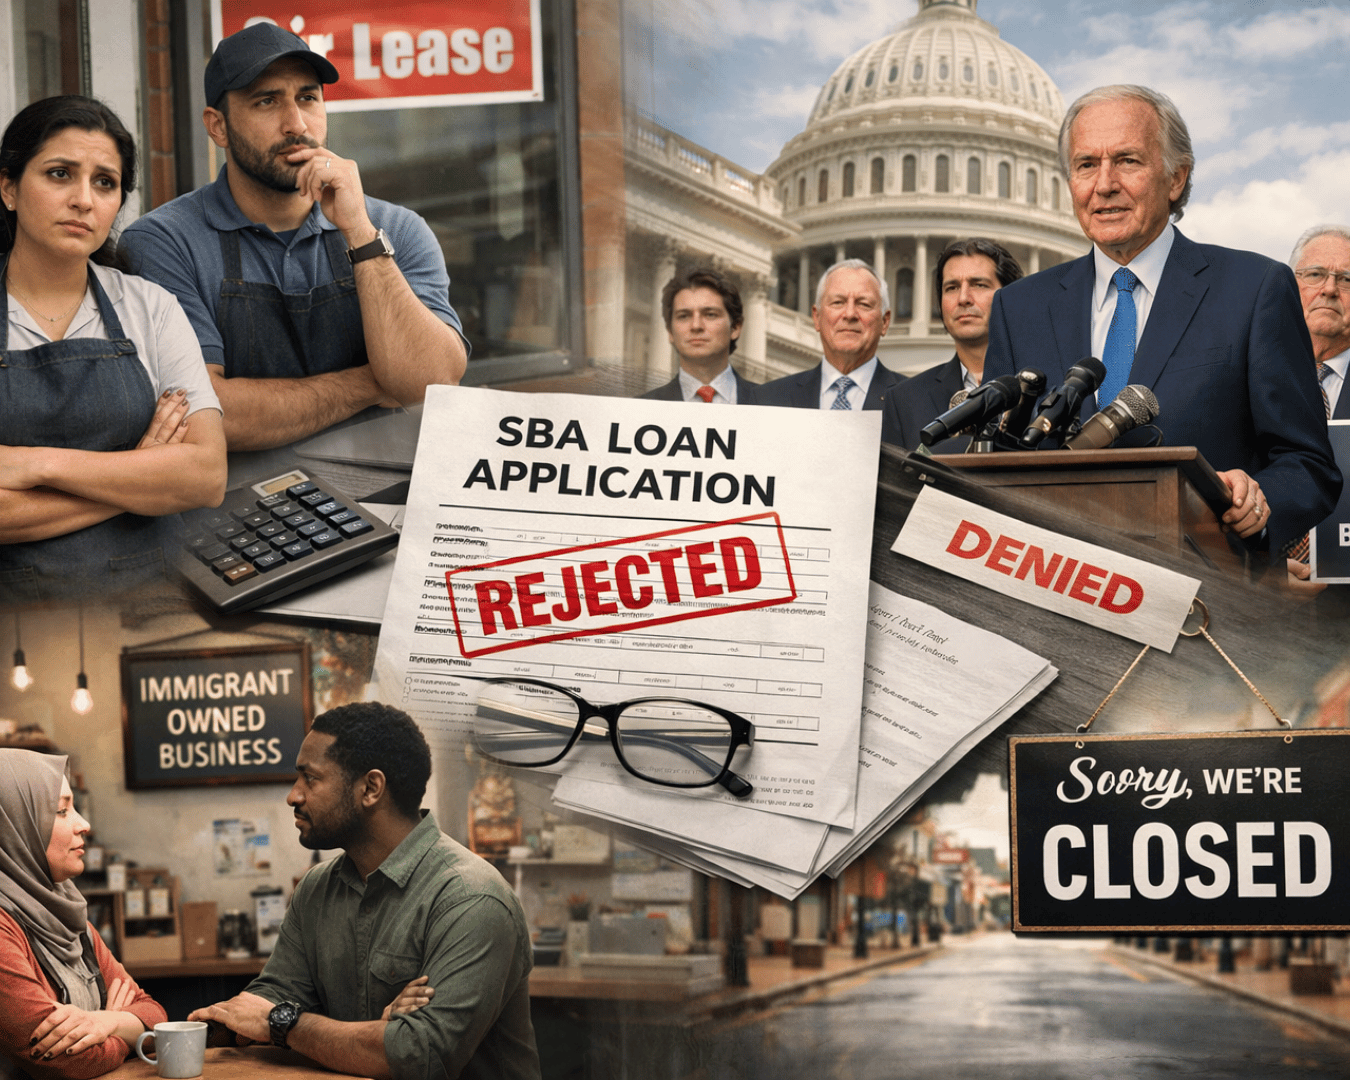
A dramatic reduction in small business lending has sparked concern among lawmakers and entrepreneurs alike, following the implementation of new Small Business Administration (SBA) policies in 2025. These changes, which include stricter citizenship verification rules and heightened lending requirements, have resulted in a 46% drop in SBA loans between June and August 2025, raising alarm about their potential impact on small businesses and local economies.
New Rules Target Non-Citizen Ties
At the heart of the issue are revised eligibility standards that make it significantly more difficult for businesses with any non-citizen ties to qualify for SBA loans. The policies, introduced by the Trump administration, require more stringent documentation of citizenship status. Businesses with even a single non-citizen owner, investor, or key employee, including individuals with Deferred Action for Childhood Arrivals (DACA) status and certain visa holders, are now barred from receiving SBA financing. These restrictions apply even if the business is majority-owned by U.S. citizens.
Lawmakers have expressed their frustration with these policies, which they argue unfairly target immigrant communities and hinder economic growth. "These new requirements hurt any small business owned or operated even in small part by noncitizens", said Ranking Member Edward J. Markey (D-Massachusetts) in a letter signed by 18 other Democratic lawmakers. "Small businesses use SBA loans to create jobs and invest in their operations. Unfortunately, the Trump administration is demonizing immigrant communities and picking winners and losers, rather than basing lending decisions on a small business’s ability to repay a loan."
sbb-itb-a3ef7c1
Additional Barriers to Financing
Beyond the citizenship requirements, the new rules also impose additional hurdles for entrepreneurs. Higher minimum credit scores and stricter underwriting processes have further complicated access to SBA loans, creating confusion and discouraging many potential borrowers. Some entrepreneurs may no longer attempt to apply for loans, fearing rejection due to the tightened criteria.
This new landscape is particularly challenging for small business owners with diverse teams or non-citizen connections. For example, businesses that receive even modest financial contributions from non-citizen friends or family members may find themselves ineligible for SBA loans. Lawmakers have criticized these policies for creating unnecessary obstacles, arguing that they stifle opportunities for growth and job creation.
Ripple Effects on Local Economies
The consequences of reduced small business lending could extend beyond individual entrepreneurs, potentially affecting entire communities. Small businesses often serve as vital drivers of local economic growth, providing jobs and supporting broader economic development. By restricting access to capital, these policies could hinder the ability of small businesses to expand, innovate, and contribute to the economy.
Markey and his colleagues have called on the SBA to reconsider its approach. They are urging a return to the previous policy, which allowed businesses owned by U.S. citizens, nationals, and lawful permanent residents to qualify for loans. The lawmakers argue that such a move would better align SBA lending practices with the needs of small businesses while fostering economic opportunity.
Lawmakers Push for Answers
Democratic lawmakers have demanded answers from the SBA, setting a deadline of January 8, 2026, for a response. They have posed several critical questions, including how many businesses have been denied loans due to the new policies and what guidance has been issued to lenders to ensure compliance. Additionally, they are seeking clarification on why individuals with lawful immigration statuses have been excluded from accessing SBA loans.
As small business owners navigate these evolving policies, the debate over their impact continues. For many, these changes highlight broader questions about the role of immigrant entrepreneurs in driving economic growth and the need for policies that support, rather than hinder, small business success.
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.
Disclaimer: The information provided in this article is for general informational purposes only and does not constitute legal, tax, or financial advice. Always consult with a qualified attorney, tax advisor, or other professional counsel before making any decisions based on this content.
 Samson JagorasPrincipal & CEO/CIOJanuary 10, 2026