SaaS Valuation Tools: Guide for Buyers
Buyer workflow for SaaS valuation: clean financials, run ARR/EBITDA/SDE/DCF, benchmark comps, and test lender coverage.
 Samson JagorasPrincipal & CEO/CIOSeptember 15, 2026
Sell your business for maximum value
Our sell-side advisors package, market, and negotiate your exit to qualified, verified buyers — confidentially.
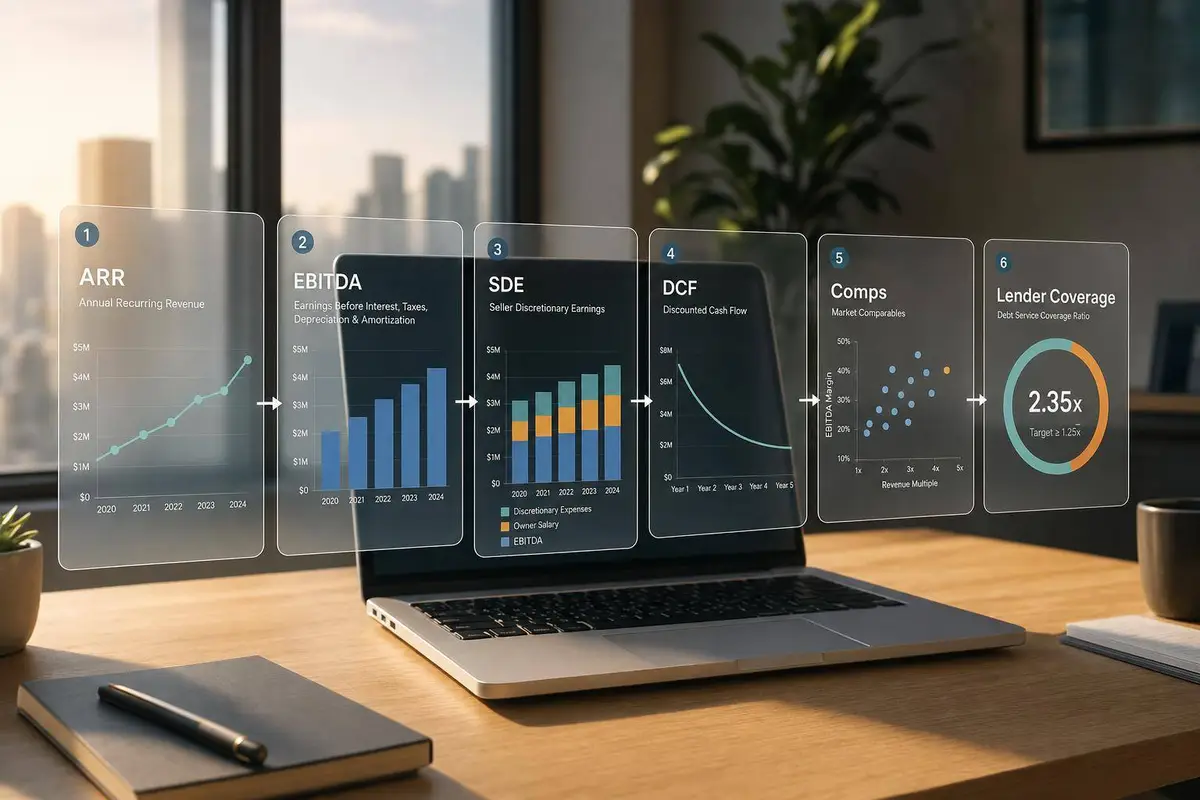
Most bad SaaS bids start with one number. I’d use a tool as a process: clean the numbers, test ARR, EBITDA, SDE, and DCF side by side, compare the result to peer deals, then check whether the debt can hold up.
Here’s the short version:
- I’d use SDE for small founder-led SaaS deals, often under $5 million in revenue
- I’d use EBITDA for mature software companies with steady profit
- I’d use ARR multiples when recurring revenue tells more than current earnings
- I’d use DCF to see if the price still works when cash flow is forecast out
Before I trust any output, I’d clean the inputs:
- Pull 24–36 months of monthly financials
- Split true recurring revenue from services, setup fees, and pass-through charges
- Check gross margin, churn, NRR, and customer concentration
- Reconcile deferred revenue and billing data
Then I’d pressure-test the value:
- Compare against private SaaS comps
- Adjust for retention, churn, concentration, founder dependence, and services mix
- Build base, downside, and upside cases
- Run lender tests like DSCR, often around 1.15x to 1.25x minimum
- Set a bid range and a hard walk-away price
One detail from the article says a $1 million SBA 7(a) loan at 10.5% over 10 years is about $13,000 per month in debt service. That’s the kind of math I’d want in the model from day one.
If I were buying a SaaS company, I would not ask, “What’s the multiple?” I’d ask, “What price still works after cleanup, comps, downside cases, and lender review?”
How to Value a SaaS Company | Peak Business Valuation

sbb-itb-a3ef7c1
Set Up the Model and Clean the Inputs

SaaS Valuation Methods Compared: ARR, EBITDA, SDE & DCF
Before you price the deal, clean the model so the bid reflects normalized economics, not messy reporting. A valuation model is only as good as the numbers going into it. The job here is simple: get GAAP results lined up with normalized cash flow, then gather inputs that can hold up in diligence.
Build a Buyer-Grade Data Intake
Start with at least 24–36 months of monthly financial statements, a detailed MRR/ARR schedule, and a customer-level revenue breakdown that shows contract value, billing frequency, renewal dates, and term length. Track churn, NRR, gross margin, CAC payback, and customer concentration.
Use these as baseline screens:
- Gross margin above 60%
- Monthly churn below 5%
- Customer concentration below 20% of ARR
- NRR above 100%
If the business shows 75%+ gross margin, sub-2% churn, under 10% concentration, and 110%+ NRR, quality looks stronger. These are the early screens both buyers and lenders tend to care about most.
Also flag any deferred revenue on the balance sheet and reconcile it to billing and contract activity. Record the source for each metric so the model is auditable. This is the dataset you need before sizing the bid or debt capacity.
Reconcile Revenue Before Applying Any Multiple
Do not apply a SaaS multiple to blended or overstated revenue. Before touching a multiple, split revenue into clear buckets: contractual ARR, annualized current MRR (current month × 12), usage-based revenue, one-time onboarding and implementation fees, professional services, and pass-through charges.
Only contractual subscription ARR and normalized MRR belong in the recurring revenue base. Everything else should be modeled on its own or handled with caution. Say a business reports $2.0 million in ARR plus $400,000 in implementation revenue. The ARR multiple should sit on the $2.0 million, while the $400,000 gets modeled separately.
Build an explicit Adjusted ARR figure and document the bridge from reported revenue to that adjusted number. That way, a lender reviewing the package can follow the logic without guessing.
Once recurring revenue is isolated, test value with more than one method. One multiple can tell a nice story. A few methods side by side usually tell the truth.
Run Multiple Valuation Methods in Parallel
Run at least four methods next to each other. Each one tests a different view of value, and the gap between them often shows where the risk or upside sits. Buyers use that spread to judge whether the company is mainly a growth story, a cash-flow story, or a risk-adjusted deal.
| Method | Best Use Case | Key Inputs | How Buyers Use It |
|---|---|---|---|
| ARR Multiple | Growing B2B SaaS with strong recurring revenue | Adjusted ARR, NRR, churn, gross margin, growth rate | Main method for subscription-led businesses; mature B2B SaaS often trades at 3x–6x ARR, growing businesses at 6x–10x ARR, and high-growth assets at 10x–15x+ ARR |
| EBITDA Multiple | Mature, profitable SaaS with stable earnings | Normalized EBITDA, revenue stability | Common in lender and PE underwriting; lower middle market SaaS often trades at 10x–18x EBITDA |
| SDE Multiple | Small, founder-led SaaS under $5M revenue | Adjusted SDE, owner compensation add-backs | Common for smaller owner-operated businesses; typical range 3x–5x SDE, with stronger assets reaching 8x |
| DCF | Stable, cash-generative SaaS | Forecast cash flows, discount rate, terminal value | Used as a sanity check to test whether the forecast supports the purchase price |
Use the spread to spot risk, upside, and the assumptions that need a closer look. When methods disagree, that tension usually points to the real underwriting issue. If the ARR multiple suggests a price that the DCF cannot support under reasonable assumptions, the gap usually means the bid is too aggressive or the inputs are too optimistic.
Keep every adjustment documented: revenue classification, expense add-backs, deferred revenue treatment, and the assumptions used to bridge reported numbers to underwriting numbers.
With normalized inputs and parallel outputs in place, the next step is to calibrate them against comparable SaaS businesses.
Use Peer Comps to Set a Realistic Valuation Range
Start with comparable private SaaS deals, then adjust the multiple for quality and risk. Once revenue and margins are normalized, peer comps help turn the model into a valuation range you can actually defend.
Pick Comparable SaaS Businesses That Match the Target
Don’t lean on broad SaaS benchmarks. They’re too blunt to be useful.
Instead, match peers based on the things that shape value in a small or mid-sized SaaS deal:
- ARR band
- End market
- Growth rate
- Gross margin
- Retention
- Go-to-market motion
For example, a sub-$5M ARR vertical SMB SaaS business growing 20%–30% with 75%+ gross margin is not the same as a $5M–$15M ARR midmarket SaaS company growing 30%+ with an enterprise sales motion. That kind of detail makes the multiple range much easier to back up with lenders or investors.
As a starting point, SaaS Capital's 2025 dataset puts the median private valuation at 4.8× ARR for bootstrapped B2B SaaS and 5.3× ARR for equity-backed peers. Those private comps should be the anchor. Public SaaS indices are better used as a quick gut check to see whether the range makes sense directionally.
Adjust the Multiple for Quality and Risk
After you set the peer median, adjust it based on the company’s actual staying power and risk profile.
Retention is a big one. Companies with NRR above 120% have traded at a 63% premium to the SaaS index median - about 9.3× EV/TTM revenue versus 5.7× for the broader index. At the other end, companies below 100% NRR have traded at a 46% discount, or about 3.1× EV/TTM revenue.
Small metric gaps can have a big effect on value. A 1 percentage point difference in churn can produce a 12% valuation impact over five years, and revenue concentration above 10% from one customer often leads to a 20%–30% discount compared with more diversified peers.
Here’s a simple way to think about those adjustments:
| Quality Factor | Premium Case | Base Case | Discounted Case |
|---|---|---|---|
| NRR | Above 120% | Near market average | Below 100% |
| Monthly Churn | Very low | Moderate | Elevated |
| Customer Concentration | Diversified customer base | Some concentration | Heavy concentration |
| Gross Margin | Strong and durable | Solid | Weaker |
| Rule of 40 | Strong | Mixed | Weak |
| Founder Dependence | Low | Moderate | High |
| Services Mix | Low | Moderate | High |
| Implied Multiple vs. Peer Median | Premium | Around peer median | Discount |
Use the base case as the market anchor. Treat the discounted case as the level you should be able to defend under diligence. Save the premium case for businesses where the metrics clearly support it. Then carry that range into forecasting and lender testing.
Get a Quality of Earnings analysis you can trust
Build Forecasts, Run Sensitivities, and Test Lender Fit
Once you have a valuation range, the next job is to turn it into an operating model. That means building forecasts from real business drivers, pressure-testing the assumptions that matter most, and checking whether lenders will back the deal. In plain English: convert the range into operating assumptions you can defend.
Build a Forecast from Revenue and Margin Drivers
Take the valuation range and turn it into a lender-ready model built from the core SaaS inputs: starting ARR, logo churn, net revenue retention (NRR), new logo adds, expansion revenue, pricing, gross margin, headcount by function, and cash conversion from billing terms, collections, and deferred revenue.
This is where you find out whether the peer-based valuation still makes sense when you run it through actual operating performance.
For a U.S.-based B2B SaaS company with $4,000,000 ARR and $800,000 EBITDA, build three cases off the same driver sheet:
| Case | ARR Growth | NRR | Annual Churn | EBITDA Margin |
|---|---|---|---|---|
| Base | 20% | 115% | 10% | 25% (year 3) |
| Downside | 8% | 105% | 15% | 18% |
| Upside | 28% | 120% | 8% | Expanding |
Each case needs a clear operating story behind it. Don't just move percentages up and down because it looks neat in Excel. Lenders and equity investors want to know why the case plays out, not just what the output says.
Run Sensitivities on the Variables That Move Value Most
After the three-case model is built, run sensitivities that change one or two drivers at a time and show the effect on enterprise value, leverage, and returns. The main value drivers are ARR growth rate, logo churn, NRR, EBITDA margin, and customer concentration.
A simple way to do this is with a two-axis sensitivity table. For example, put growth rate on one axis, from 10% to 30%, and annual churn on the other, from 8% to 20%. Then use each cell to show the resulting EV or equity IRR. That lets you see, fast, which combinations support the purchase price and which ones fall apart.
One thing comes up again and again in SaaS underwriting: NRR and EBITDA margin are the strongest levers. A move from 105% to 120% NRR can increase both the valuation multiple and the amount of debt a lender is willing to provide. At the same time, include at least one concentration shock. Model what happens if the largest customer, or the top 10% of ARR, churns in full. If the business and capital structure can't absorb that hit, the deal structure needs to change before the bid goes out.
Compare Equity Value Against Lender Underwriting
Equity investors and lenders are looking at the same company, but they're asking very different questions. Equity cares about growth, NRR, and long-term returns. Lenders care about whether cash flow is steady enough to pay debt on time.
| Metric | Equity Lens | Lender Lens |
|---|---|---|
| Main test | ARR multiple, EV/EBITDA, IRR | DSCR, adjusted EBITDA, cash flow reliability |
| What it answers | What is the business worth? | Can it service the debt? |
| Key drivers | Growth, NRR, margin, churn | Collections, billing cadence, deferred revenue, margin durability |
| Output | Valuation range and return profile | Loan amount, leverage, covenants, amortization fit |
Most SBA and conventional lenders want a minimum DSCR of 1.15x to 1.25x, and many sponsors aim for 1.5x to 2.0x or higher for breathing room. They also look closely at billing cadence. A business with mostly monthly contracts and slow collections will be viewed very differently from one with annual upfront billing.
Deferred revenue matters here too. If GAAP revenue recognition trails cash collection, lenders will want to tie bank statements and processor data back to the ARR schedule before they commit to a loan amount.
If the debt doesn't pass the coverage test, something has to give: price, capital stack, seller paper, or amortization. Map the same operating cases to lender criteria before you submit the bid, so you're making those changes early instead of after credit pushback.
Use the lender-adjusted base case as the bid anchor in the investor memo.
Turn the Model Into an Investor Memo and Final Bid
Present the Valuation Case in an Investor Memo
Once the lender-fit base case is set, the model needs to do more than crunch numbers. It needs to become a decision document people can read, debate, and approve. A strong investor memo turns model outputs into a clear buy / no-buy call. After that, those same outputs should roll straight into a committee-ready bid package.
The thesis section should point to the exact metrics that make the deal worth pursuing: NRR, logo churn, CAC payback, LTV/CAC, and historical ARR growth from the cleaned input set. The valuation section should then show where the final bid sits inside the peer-comp range and whether the DCF base case ($9.2M) and downside case ($7.8M) back it up or push against it.
The memo should also lay out the capital stack in plain English and check it against lender limits in both the base and downside cases before the deal goes to committee. Spell out the proposed structure:
- Senior debt
- Seller note
- Earnout
- Rollover equity
- Sponsor equity
Then confirm that the structure clears coverage and covenant tests in both cases.
Scenario outputs should drive the return case, not sit buried in a spreadsheet tab no one opens. Put IRR, MOIC, and cash-on-cash for each case into a simple summary table so investors can judge risk and return at a glance.
| Case | IRR | MOIC | Cash-on-Cash | Hold Period |
|---|---|---|---|---|
| Base case | 22% | 2.7x | Include model output | 6 years |
| Downside case | 12% | 1.6x | Include model output | 6 years |
A base case IRR of 22% with a 2.7x MOIC over six years reads very differently from a downside IRR of 12% with a 1.6x MOIC. Both need to be visible before anyone signs off on the deal.
Flag the Risks Most Likely to Change Price or Structure
The next step is to turn model sensitivities into pricing and structure decisions. The downside case is the best place to do that. It shows which risks should lower price and which ones are better handled through deal terms.
| Risk | Price Impact | Structural Response |
|---|---|---|
| Weak retention / high churn | Lower EV/ARR multiple | Earnout tied to retention milestones |
| Top 3 customers > 30% of ARR | 0.5x–1.0x multiple discount | Larger seller note; earnout contingent on key renewals |
| Non-recurring revenue > 20% | 0.5x–1.0x discount on that revenue tranche | Earnout tied to growth in true ARR only |
| Implementation-heavy delivery | Lower margin assumptions | Conservative leverage; SBA debt over aggressive conventional |
| Key-person dependence | Minimal direct pricing impact | Retention plans, non-competes, seller rollover equity, and transition milestones |
The memo should also state the hard walk-away price in plain terms. For example, the buyer should not bid above the price where downside IRR drops below 10%. That one rule can keep a team from getting pulled into emotional bidding when the seller pushes for more. If anyone wants to go above the recommended bid band, that should require investment committee approval and a written reason.
Conclusion: A Buyer Workflow for SaaS Valuation Tools
The memo should end with one clear bid and one clear walk-away price. The process should move in a straight line: from raw data to a bounded, risk-adjusted bid. Start with the right valuation lens. Normalize the inputs. Triangulate across EV/ARR, EV/EBITDA, and DCF. Benchmark against peer comps, then adjust for quality and risk. Build base and downside cases from actual operating drivers. Run sensitivities on NRR and logo churn. Check that the capital structure clears lender coverage tests. Then turn all of that work into an investor memo where every conclusion ties back to a specific model output. That is the disciplined path to a confident bid.
FAQs
Which valuation method should I trust most for a SaaS acquisition?
Trust the method that fits the business: use revenue/ARR for growth-focused SaaS, and EBITDA for deals centered more on cash flow.
Clearly Acquired helps buyers size up price ranges with core SaaS metrics like ARR/MRR, churn, NRR, CAC/LTV, and customer concentration. It also connects valuation to lender fit, comps, projections, and sensitivity analysis.
How do I normalize ARR before applying a multiple?
Start by normalizing the financials so they show true recurring revenue and the company’s earning power. Strip out one-time items and personal add-backs, then review core SaaS metrics like churn, NRR, CAC, and LTV to check revenue quality.
Then compare the business against similar companies. Adjust for growth, customer concentration, and management depth, and pressure-test best-, worst-, and base-case forecasts. Use those inputs to set a defensible valuation range before you apply a multiple.
What can cause a lender to reject a SaaS deal?
A lender may pass on a SaaS deal when the numbers don’t hold up under scrutiny. That often happens when the financials haven’t been normalized well, add-backs are vague, recurring revenue such as ARR and MRR hasn’t been verified, or the projections and debt service model look too aggressive.
They also spend a lot of time on cash flow stability. If the business can’t show steady, believable cash generation, the deal gets harder to finance.
For buyers, that means doing the homework up front. Use verified peer comparisons, pick the valuation method that fits the company’s stage, and pressure-test assumptions around growth and churn before taking the deal to a lender.
Related Reading
Sell with advisors who maximize your outcome
From valuation and positioning to closing the deal, we run a competitive process to get you the best terms.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.