Phased Ownership Transfer: 3 Exit Plan Stages
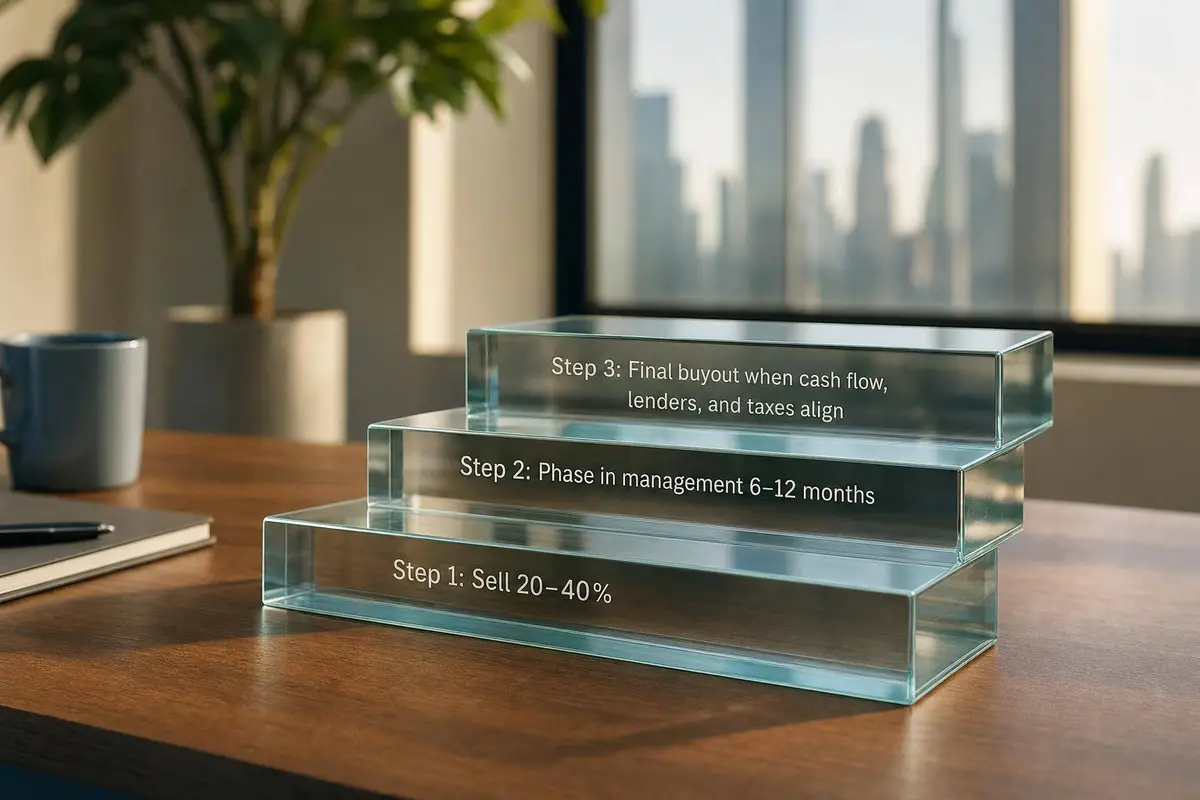
Three-stage exit: sell 20–40% first, phase in management over 6–12 months, then complete the final buyout when cash flow, lenders, and taxes align.
 Samson JagorasPrincipal & CEO/CIOSeptember 12, 2026
Get matched with the right lender for your business
Compare offers from our vetted network. Pre-qualify in minutes — no impact to your credit.
If you want to lower the odds of a failed business sale, don’t try to transfer everything at once. I’d treat the exit as a 3-stage plan over 3 to 5 years: sell a 20%–40% stake first, shift day-to-day control over 6 to 12 months, then finish the last buyout when cash flow, lender approval, and management readiness line up.
Here’s the short version:
- Stage 1: I sell a minority stake and set the price, financing, and tax setup early.
- Stage 2: I hand over management in steps, with written milestones and clear decision rights.
- Stage 3: I close the final sale using fixed triggers like EBITDA targets, note paydown, or refinance approval.
A phased exit often fits better when:
- the next owner is not ready yet
- lenders want to see stable results
- buyer and seller disagree on valuation
- I want income over time instead of one lump sum
A few numbers shape the plan:
- SBA 7(a) deals often work for purchases under $5 million
- buyer equity is often 10%–20%
- seller financing often covers 10%–30%
- small-business pricing is often based on 3x–6x normalized EBITDA
- many lenders want DSCR around 1.15x–1.35x

3-Stage Phased Business Exit Plan: Timeline & Key Milestones
Crafting an effective business exit strategy

sbb-itb-a3ef7c1
Quick comparison
| Stage | What moves | Common timing | Main focus |
|---|---|---|---|
| 1. Minority sale | Ownership interest | Start of plan | Price, debt, seller note, tax setup |
| 2. Control handoff | Management authority | 6–12 months | Roles, milestones, pay, approvals |
| 3. Final buyout | Remaining equity and voting rights | End of plan | Refinance, consents, clean exit |
The core idea is simple: ownership, control, and payment do not need to move on the same day.
Stage 1: Structure the Minority Equity Sale
Stage 1 moves a meaningful share of ownership while the seller still keeps control.
Choose the Stake Size, Ownership Instrument, and Pricing Method
Stage 1 often transfers 20%–40%, with the size tied to cash flow and how ready the successor is.
If the successor is still learning the business, starting with 20%–25% and tying later tranches to performance milestones is often the safer play. If the successor already runs day-to-day operations, a 30%–40% opening stake may line up better with their role and commitment. Either way, the first transfer should fit the full 3-stage roadmap. For example: 30% now, another 30% at the management handoff, and the final 40% at close. That keeps the path to 100% ownership realistic and financeable.
The ownership instrument affects control, economics, and tax treatment. Non-voting units or shares make sense when the buyer should get the economic upside first and voting control later. Profits interests can work well in LLCs when the goal is to give the successor upside from future growth without handing over existing equity value. The catch is financing: SBA and bank lenders often prefer ownership stakes that are clearly defined and transferable, so profits interests can be harder to fund with debt.
Price the stake using a method a lender can underwrite, often 3x–6x normalized EBITDA. Putting that pricing formula into the shareholder agreement or operating agreement can also help set the rules for future tranches, which cuts down on fights later. If the facts are messy, an independent third-party valuation can add objectivity and lower the odds of a dispute.
Once the ownership instrument is set, the next step is simple: price it in a way lenders can get comfortable with.
Fit the Financing to Cash Flow and Lender Requirements
Stage 1 financing usually blends buyer cash, debt, and seller financing.
SBA 7(a) loans often fund acquisitions under $5 million. They can cover goodwill and working capital, offer terms of up to 10 years with no balloon payment, and usually call for a debt service coverage ratio of about 1.15x–1.35x, depending on lender policy. Buyers also usually need to put in 10%–20% of the total project cost as equity. In SBA-financed partial ownership changes, the deal usually must be set up as a stock or membership-interest purchase, not an asset deal. And in most cases, all new equity owners must be co-borrowers on the loan.
Seller notes usually fill the gap between senior debt and the agreed price. In small-business deals, seller financing often covers 10%–30% of the total purchase price, with interest rates commonly in the 5%–10% range and terms of 3–7 years. If an SBA loan is in the mix, the seller note must be subordinated to the senior debt. It also may need to go on full standby for 12–24 months to meet SBA rules. This is where cash flow discipline matters. The payment terms need to fit projected free cash flow, with DSCR staying comfortably above the lender’s minimum.
After the capital stack is in place, tax treatment needs to be locked down before anyone signs.
Address Tax Timing Before Signing the First Transfer
Set the tax structure before signing.
When the seller transfers stock or LLC membership interests, gain above basis is generally taxed at long-term capital gains rates, which top out at 23.8% including the Net Investment Income Tax for most sellers. That is often better than an asset sale, where prior depreciation may be recaptured and taxed at ordinary income rates, up to 40.8% including NIIT. That gap is a big reason many sellers lean toward stock or interest sales when the structure permits it.
Installment sale treatment can be especially useful in Stage 1. If the seller gets paid over time through a seller note or deferred closing payments, gain can be recognized as each payment comes in instead of all at once. That lines up the tax bill with the cash coming through the door. But there’s a trap here. If the note is pledged as collateral, the IRS may treat it as payment received and tax the deferred gain right away. The same issue can come up if the note is sold, gifted, or canceled.
Purchase price allocation becomes a big deal in asset deals. Under IRS Section 1060, the allocation decides how much of the price is taxed as ordinary income versus capital gain, and both buyer and seller must file consistent Form 8594 returns. If the allocations do not match, both sides face audit risk. That is why qualified tax counsel should be involved before anything gets signed. The structure picked in Stage 1 sets the tax baseline for every later step in the transfer.
With the first transfer priced, financed, and taxed, Stage 2 can shift operating control in milestones.
Stage 2: Hand off management and control
After the minority sale closes, Stage 2 is where authority starts to move. Not just equity. The day-to-day running of the business shifts to the successor, even though ownership is still split.
Transfer operating authority in defined milestones
A normal handoff takes 6 to 12 months. At first, the successor sits in on meetings and customer calls. Then they start leading budgets, hiring, and weekly team calls. After that, they become the main point of contact for employees, vendors, and key accounts.
Write down each step. Include the effective date and the trigger tied to that step, such as revenue goals, retention thresholds, or one clean quarter of reporting. If the handoff is vague, people start guessing who owns which decision. That confusion is one of the most common reasons Stage 2 gets stuck before Stage 3 can close.
Once the operating sequence is clear, the legal paperwork needs to line up with that new authority.
Separate economic ownership from voting control
Economic rights and voting rights do not have to move at the same time. A buyer may receive most cash-flow rights while the seller keeps certain voting powers until a later trigger date. The deal structure decides when each right moves.
This split helps spell out who gets the cash flow and who holds control:
| Feature | Economic Ownership | Voting Control |
|---|---|---|
| What it covers | Profits and exit proceeds | Strategy, hiring, and budgets |
| How it transfers | Equity rollover or seller-note structure | Board seats and approval thresholds |
| Governance tool | Shareholder or operating agreement | Reserved matters and milestone schedule |
Update the operating agreement or shareholder agreement so it matches the current setup. That usually means board seats, approval thresholds, reserved matters, and a sunset date for seller consent.
Once those rights are clear, pay terms and covenant terms should back up the new chain of command.
Align incentives, covenants, and seller-note protections
When the successor starts carrying real operating responsibility, compensation should change too. A base salary plus a performance bonus tied to EBITDA, cash collections, or customer retention is common. If the successor also holds equity, profits interests or phantom equity can give them more upside without an immediate cash payment.
Put simply: pay should match accountability. If the successor now owns budget performance and staffing, their comp plan should show that before the handoff is finished.
Review loan, lease, customer, and license agreements for consent clauses that may be triggered by a control change. Then tighten seller-note covenants just enough to guard against downside, without sliding back into seller control.
When those performance triggers are met and control feels steady, the final transfer can close.
Stage 3: Close the final transfer and exit cleanly
Once management control has shifted, Stage 3 turns that control into full ownership. The rest of the equity moves to the buyer, the seller’s governance rights stop, and one owner takes full control.
Set clear triggers for the final buyout
An open-ended close date gives either side room to stall. The fix is simple: put specific triggers into the original deal structure.
| Trigger Type | Common Metrics/Conditions | Typical Duration/Threshold |
|---|---|---|
| Financial performance | Revenue or EBITDA target | Agreed in advance |
| Debt readiness | Lender refinance approval | Commitment in place |
| Seller-note paydown | Principal balance reduction | Per the note schedule |
| Transition milestones | Key staff retained, systems transferred | Milestones completed |
| Fixed date | Calendar-based close | Specific date set in the deal documents |
Third-party consents matter here too. Landlords, franchisors, key customers, and licensing bodies may each need notice or approval when control changes for good. Review those agreements early. Then map out which consents are needed, who sends the notice, and how long each approval takes. Track those approvals as closing conditions so they don’t slow down the final transfer. Miss just one, and a phased exit can still fall apart at the last mile.
Complete the legal transfer and remove legacy rights
The final close should deliver a clean handoff of the remaining equity, a valuation true-up if needed, and a payoff or amendment for any seller note still outstanding.
Before closing, strip out every seller right that’s still hanging around. That includes canceling or reassigning board seats, releasing approval thresholds in the operating agreement, and ending any personal guarantees on business debt where the lender agrees. The key documents usually include:
| Document | Purpose |
|---|---|
| Promissory Note | Outlines principal, interest rate, and maturity |
| Amortization Schedule | Breaks down interest and principal for reporting |
| Equity assignment / membership interest assignment | Transfers remaining ownership interest to the buyer |
| Security Agreement / UCC-1 | Details collateral and legal claims on assets |
| Payment Log | Tracks payments for Form 6252 filings |
After close, there shouldn’t be any confusion about who controls cash, who votes on strategy, and who sits on the board. If the paperwork leaves any of that fuzzy, fix it before the ink dries.
Define the seller's post-close role and end date
If the seller still holds key relationships or technical know-how, use a short consulting agreement with a clear scope and a fixed end date. Keep it tight. And make sure it gives the seller no operating authority after close.
Once the seller is fully out, map the full Year 1-to-close timeline, capital stack, and closing sequence.
Build the full timeline, capital stack, and closing plan
With the three stages set, put timing, financing, and closing conditions into one clear sequence before the first transfer.
Map the deal from Year 1 to final close
Lay out the deal as one connected path: pre-exit planning, minority sale, management handoff, covenant tracking, and final buyout.
Owners often spend 12 to 24 months getting ready for exit. That work usually covers valuation, tax exposure, and lender prequalification.
Starting early gives you more room to work. You have time to clean up financials, deal with lender consent rules and covenant risks, and set up the seller note so it doesn’t clash with senior debt. Start late, and your choices tend to shrink. Financing can get tighter. Structuring can get messier. That’s when small issues turn into deal problems.
This sequence also shows when each approval, funding source, and document needs to be in place.
Use the right financing tool at each stage
The capital stack should change as deal risk comes down. Early on, lenders tend to be careful. During the minority sale stage, the deal often depends more on:
- a larger buyer equity contribution
- a seller note
- limited senior debt based on cash flow
As the handoff moves forward and transition risk drops, lenders may support more of the transaction. By the final buyout, SBA 7(a), SBA 504, or conventional debt can take on a bigger share because the business has a clearer track record under the new setup.
At that stage, the seller note may be refinanced or paid down. If there’s still a gap between senior debt and the buyer’s equity, mezzanine debt or outside equity can help fill it.
| Stage | Primary Financing Tool | Key Constraint |
|---|---|---|
| Minority sale | Seller note + limited senior debt | Lender caution; note typically subordinated |
| Management handoff | Existing debt; no new equity usually added | Covenant compliance; DSCR maintenance |
| Final buyout | Senior debt refinance + seller note payoff | Business performance; lender approval |
If SBA financing is part of the deal, the seller note is usually subordinated to the senior lender and may need lender consent plus payment limits. In some setups, the note may also require a standby period before the seller can begin collecting payments.
Key takeaways for a workable 3-stage exit plan
Set exit goals early. Match financing to cash flow. Put milestones in the deal documents. Make the final close trigger-based and clean.
FAQs
Is a phased exit better than a full sale at once?
It can be, depending on the deal.
A 3-stage transfer often looks like this:
- A minority equity sale, sometimes with seller notes to help bridge valuation gaps and reduce the buyer’s cash needs
- A gradual management handoff, so knowledge and leadership move over time instead of all at once
- A final close after tax, legal, and lender requirements are addressed
This kind of setup can lower transition risk. But the right structure still depends on timing, taxes, and lender rules.
How do I know what stake to sell first?
In a 3-stage transfer, owners often start by selling a minority equity stake. If there’s a gap between what the buyer will pay and what the seller wants, that gap can be filled with seller notes or 721/rollover-type structures. At the same time, both sides need to plan for tax effects, including asset vs. stock sale treatment, installment reporting on Form 6252, and the terms tied to any seller note.
After that, management handoff begins through a phased knowledge transfer. This is the part where the seller gradually passes along know-how, key relationships, and day-to-day context so the new team isn’t thrown in cold.
The final close comes after approvals are in place, legal documents are signed, purchase-price allocation is handled on Form 8594, and post-sale transition support is mapped out.
What can delay the final buyout?
The final buyout can get delayed when anything holds up the last stage of a phased ownership transfer.
A few issues show up again and again: an incomplete leadership handoff, deal terms that still aren’t settled, tax planning questions, and problems with corporate records, licensing, or closing requirements.
In many small business exits, these delays show up late in the process. That often happens after minority equity sales, when the management transition is still being worked through, or when seller-note terms still need to be fully aligned before closing.
Related Reading
Find the right lender for your business
Whether it's working capital, an SBA loan, or acquisition financing — we'll match you with the right capital partner.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.