Book Value Analysis for Asset-Based Acquisitions
Turn book value into an underwriting tool: verify AR, inventory, and PP&E; apply appraisals and haircuts to test collateral vs. debt.
 Samson JagorasPrincipal & CEO/CIOSeptember 7, 2026
Get matched with the right lender for your business
Compare offers from our vetted network. Pre-qualify in minutes — no impact to your credit.
Book value can help you start a deal review, but it should never decide the deal on its own. If I’m looking at an asset-heavy business, I want to know three things fast: what the balance sheet says, what the assets could support for debt, and what those assets might bring in a sale if things go wrong.
Here’s the short version:
- Book value is an accounting number, not a market price.
- A/R, inventory, equipment, and real estate may support debt, but only after cuts, haircuts, and verification.
- Older assets can be understated if depreciation is heavy.
- Inventory and receivables are often overstated if records are stale, slow-moving, disputed, or past due.
- Goodwill and most intangibles usually do little for collateral support.
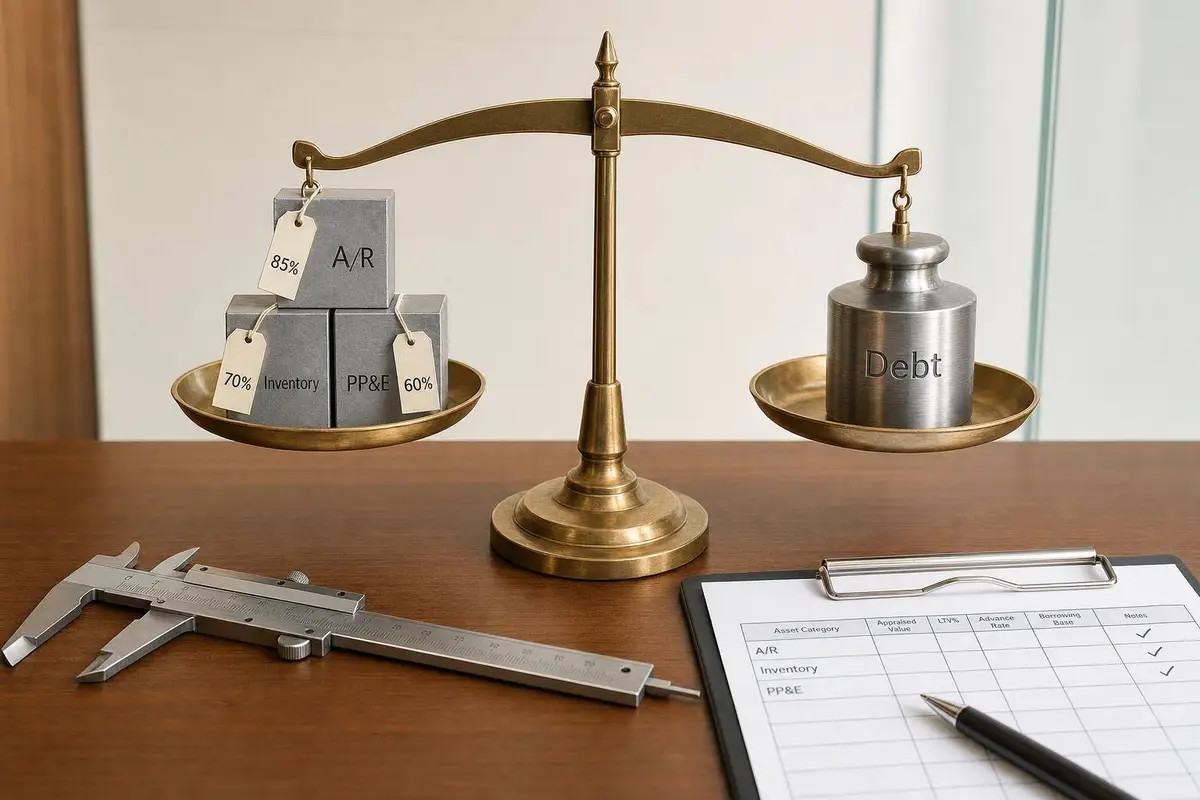
- Lenders often use rough advance rates like 80%–85% of eligible A/R, 50%–65% of eligible inventory, and 70%–85% of equipment NOLV.
- Downside can be harsh: distress research cited in the article shows combined recovery for fixed assets, inventory, and receivables averaging about 23% of total book value.
If I had to boil the full article down to one line, it would be this: start with reported book value, strip out weak assets, mark the rest to what a lender or buyer could actually recover, and then test whether that supports the purchase price and debt load.
A few checks matter most:
- Review A/R aging
- Review inventory by SKU, age, and location
- Tie PP&E to the fixed-asset ledger
- Compare equipment book value to appraised NOLV
- Remove or discount items that are missing, obsolete, disputed, or hard to pledge
- Compare adjusted collateral to senior debt, total price, and the equity cushion
Net Book Value Explained #nbv #depreciation

sbb-itb-a3ef7c1
Quick Comparison
| Measure | What it tells me | What it does not tell me | Best use |
|---|---|---|---|
| Book Value | Carrying value on the balance sheet | What assets would sell for today | Starting point |
| Replacement Cost | What it may cost to rebuild the asset base | What a lender would lend today | Check if the buyer is paying above or below rebuild cost |
| Fair Value | Likely market price in an orderly sale | Worst-case recovery in distress | Market check for equipment, trucks, and real estate |
| Liquidation Value | Likely recovery in a wind-down | Going-concern upside | Downside test and debt sizing |
So if you’re using book value to back a $10,000,000 deal, don’t stop at the accounting numbers. Check what is current, what is saleable, what is pledgeable, and what survives a liquidation haircut. That is the part that tells you whether the deal is built on assets or just hope.
How to Read Book Value on the Balance Sheet
Start with the balance sheet, then trace each line to the schedule behind it: A/R aging, inventory listing, fixed-asset ledger, and debt schedule. That’s where the numbers stop being accounting entries and start becoming underwriting inputs. Reported book value is just the first pass. After the balances tie back to source schedules, you still need to adjust for depreciation, write-downs, and stale records.
Here’s a simple map for turning reported balances into something a lender can actually use:
| Asset Class | How Book Value Is Reported | Common Adjustments | Underwriting Relevance |
|---|---|---|---|
| Accounts Receivable | Gross receivables less allowance for doubtful accounts | Remove balances more than 90 days past due, related-party balances, disputed items, and over-concentrated customer exposures | Primary support for the borrowing base and short-term liquidity |
| Inventory | Lower of cost or net realizable value using FIFO, LIFO, or weighted average | Discount WIP, obsolete, slow-moving, consigned, or otherwise ineligible items | Collateral for asset-based loans; tests immediate recovery value |
| PP&E | Historical cost less accumulated depreciation | Replace net book value with appraised NOLV | Long-term collateral; should be tested against condition and maintenance records |
| Intangibles & Goodwill | Intangibles are recorded at cost and amortized or tested for impairment; goodwill is tested for impairment under U.S. GAAP | Usually excluded or heavily discounted in collateral analysis | Minimal direct collateral support; more relevant to earnings-based valuation |
| Liabilities | Face value of known obligations | Include debt, lease obligations, and contingent liabilities disclosed in the notes | Helps determine how much value is left for equity |
Accounts Receivable and Inventory: Current Assets That May Support a Borrowing Base
To get to an eligible collateral number, you need an A/R aging report, usually in 30-day buckets. Then you apply lender-style eligibility filters.
Most U.S. asset-based lenders remove receivables that are more than 90 days past due, intercompany balances, disputed invoices, and foreign receivables without trade credit insurance. They also often cap exposure to a single customer at 20% to 25% of eligible AR. After those filters, lenders often advance about 80% to 85% of eligible AR.
Inventory needs the same kind of pressure test. Match the book number to the inventory listing by SKU, location, and age. Work-in-process is often excluded or capped at a much lower level. Slow-moving, obsolete, consigned, or otherwise ineligible items may also be removed or marked down hard. Finished goods and some raw materials, by contrast, often support an advance of 50% to 65% of cost.
PP&E: Historical Cost, Accumulated Depreciation, and Net Book Value
PP&E on a U.S. balance sheet is shown at historical cost less accumulated depreciation. That gives you net book value, but net book value is just unrecovered accounting cost. It does not tell you what the equipment would sell for today.
So treat net book value as a reference point, not a market value. Then test it against the fixed-asset ledger and an NOLV appraisal.
Ask for the fixed-asset ledger, the schedule that ties straight to the PP&E line. It should show each asset’s description, location, acquisition date, original cost, accumulated depreciation, and net book value. From there, cross-check it with maintenance logs and, for major assets, an independent appraisal based on net orderly liquidation value. Lenders often advance about 70% to 85% of appraised NOLV on general-purpose machinery and equipment, and about 60% to 75% of appraised value on commercial real estate.
If the business owns its real estate, separate that value from the operating business. That makes it easier to look at financing paths without mixing property value into day-to-day operations. Book value still has to be adjusted before it can carry weight in underwriting.
Intangibles, Liabilities, and Book Equity Reconciliation
The accounting equation - Assets = Liabilities + Shareholders' Equity - gives you the basic frame for checking how much reported book equity is backed by tangible assets.
Start by splitting tangible assets, such as cash, AR, inventory, PP&E, and real estate, from intangibles, such as goodwill, trademarks, customer lists, and capitalized software. Goodwill is not amortized under current U.S. GAAP, but it is tested for impairment. In collateral-focused underwriting, it is usually removed from the borrowing base because it’s hard to turn into cash in a liquidation.
After you remove intangibles and adjust tangible assets to more realistic collateral values, compare that adjusted asset base with total liabilities. That means debt, lease obligations, and major off-balance-sheet obligations disclosed in the notes. What’s left is tangible equity. That number helps you see whether the deal rests on hard assets or mostly on cash flow.
Adjusting Reported Book Value for Depreciation, Write-Downs, and Stale Records
Reported carrying values are built for accounting consistency, not economic precision. In small-business acquisitions, book value can differ a lot from economic value, and that gap can change the underwriting view. The point here isn't perfect accounting. It's getting to a number you can trust.
Use the balance sheet to test three things: remaining utility, physical existence, and realizable value. That’s how you turn carrying value into an underwriting view.
| Asset Category | Reported Book Value Basis | Diligence Adjustment Needed | Typical Direction of Adjustment |
|---|---|---|---|
| Equipment / PP&E | Historical cost less accumulated depreciation | Remaining service life, maintenance, and replacement cost | Up if fully depreciated but productive; Down if unmaintained or broken |
| Inventory | Lower of cost or net realizable value | Physical count, obsolescence, turnover, and reserve testing | Down (spoilage, damage, slow-moving stock) |
| Intangibles | Amortized historical cost | Verify active rights; exclude expired or unsupported assets | Down if expired or invalid |
How Depreciation Can Understate Useful Equipment Value
U.S. small businesses often depreciate equipment on accelerated tax schedules that front-load deductions and can drive net book value (NBV) close to zero on 5- to 7-year schedules. That treatment is valid and tax-efficient. But it says little about how long the equipment will keep working.
A fully depreciated machine may still have a lot of useful life and resale value. Valuation guidance treats equipment book value as a weak starting point in business sales because short useful lives and heavy tax depreciation are picked for tax treatment, not to show true asset value.
So if you see equipment with near-zero NBV that still runs the business, don't stop at the balance sheet. Check the site. Review maintenance logs. Then compare replacement cost using vendor quotes, dealer data, or auction results. That gives you an economic value you can defend in underwriting, separate from the accounting number. If the asset still belongs in the business, it belongs in adjusted collateral.
How Write-Downs and Impairments Can Clean Up or Distort the Picture
A large write-down or impairment charge isn't always bad news. Sometimes it shows discipline: management identified obsolete inventory or a weak asset and cleaned up the books. Under U.S. GAAP, once a long-lived asset is impaired, that loss generally cannot be reversed, so the reduced value becomes the new permanent carrying amount. That can make the balance sheet more conservative and more usable going forward.
The trouble starts when the charge has no clear operating story behind it. Watch for large one-time inventory reserve entries at year-end with no clear business reason. Also watch for sharp drops in the allowance for doubtful accounts that don't line up with better aging data. Trace big charges across three to five years of financials and ask for the internal memos or policy documents behind them. If the seller can't explain why a large charge landed in a certain quarter, that's a gap worth pushing on before close. Assets that hold up in this review belong in adjusted collateral. Assets that don't should be left out.
Stale Fixed-Asset and Inventory Records: A Hidden Underwriting Risk
Small businesses often track fixed assets and inventory in spreadsheets or old systems, and over time the ledger drifts away from what's on the ground. Old assets and obsolete inventory can stay on the books at full cost long after they stop producing value. That shows up all the time in diligence for asset-based businesses, and asset-based lenders exclude stale, slow-moving, or obsolete assets from the borrowing base for this exact reason.
Fixing this takes legwork. Reconcile the fixed-asset ledger to a physical site visit and a serial-number list. Match inventory records to a current physical count and turnover data by SKU. Any asset you can't verify physically or operationally should come out of adjusted collateral. Put plainly: if you can't confirm it's there and working, it should not support purchase price or debt capacity.
These adjustments create the collateral base used in the next support test.
Book Value vs. Replacement Cost, Fair Value, and Liquidation Value

Book Value vs. Collateral Value: Asset Advance Rates & Recovery Benchmarks
Once you've made the adjustments, the next step is to compare book value with replacement cost, fair value, and liquidation value. This is where adjusted book value stops being just an accounting figure and starts becoming an underwriting number. Buyers and lenders use these checks to pressure-test the balance sheet from different angles. Each one answers a different question, and each fits a different part of the deal review.
| Valuation Basis | Definition | Best Use in Acquisitions | Main Data Source |
|---|---|---|---|
| Book Value | Accounting carrying value | Starting point only; identifies asset categories and tax basis | Financial statements, fixed-asset ledger |
| Replacement Cost | What it would cost to rebuild comparable assets today | Buying below or above the cost to recreate the asset base | Vendor quotes, contractor estimates, industry cost indices |
| Fair Value | The price a willing buyer and seller would agree to today | Collateral underwriting; pricing assets with active resale markets | Appraisals, broker opinions, auction and marketplace data |
| Liquidation Value | Expected recovery in a non-going-concern sale, whether organized or forced | Downside testing; lender risk limits | Appraiser liquidation schedules, auction recovery data |
Replacement Cost: What the Asset Base Would Cost to Rebuild Today
Replacement cost answers a plain-English question: if you had to rebuild this asset base today, what would it cost? For older industrial and logistics assets, replacement cost can come in at 2x to 3x net book value. That gap matters.
If you're buying the asset base below replacement cost, you may have a built-in margin of safety. If you're paying above replacement cost, the deal needs support from durable cash flow or some strategic reason for the premium. Otherwise, you're paying more than it would cost to recreate the same thing from scratch.
Fair Value: Market-Based Asset Pricing
Fair value is the price a willing buyer and seller would agree to today in an orderly transaction. In other words, it's based on the market, not the accounting records.
This matters most for assets with active resale markets, like trucks, trailers, equipment, and commercial real estate. In some cases, fair value can sit well above book value because demand in the resale market is still strong. In other cases, it can fall well below book value, especially when equipment is specialized and tough to move.
Buyers and lenders usually estimate fair value using:
- Comparable sales
- Appraisals
- Broker opinions
- Marketplace data
Fair value generally sits somewhere between book value and liquidation value.
Liquidation Value: Testing Downside, Not Going-Concern Upside
Liquidation value answers the question nobody likes to ask but everybody needs to ask: what do we recover if this deal goes sideways?
Orderly liquidation value (OLV) assumes there is enough time for a marketed, organized sale. Forced liquidation value (FLV) assumes a short, distressed sale window, often 30–90 days, with limited marketing. Net orderly liquidation value (NOLV) takes OLV and subtracts selling costs. That's the net recovery number lenders care about most.
The spread between these numbers can be big. Empirical research shows that the combined liquidation value of fixed assets, inventory, and receivables averages about 23% of total book value in distress cases. Even in an orderly sale, fixed assets alone average about 35% of net book value across industries.
That's why lenders size borrowing bases to OLV or NOLV, not to book value. Buyers use the same figures to test downside before they get too comfortable with the upside. Use these metrics in the support test that follows.
Testing Whether Book Value Supports the Deal
Build a Support Test: From Reported Assets to Adjusted Collateral
Once you adjust assets to collateral value, the next job is simple: see whether those assets can support the deal. Reported value is nice to know. Lendable value is what matters.
Go asset class by asset class. Apply eligibility cuts to A/R and inventory. Then haircut equipment to appraised NOLV before you apply advance rates. The core formula is: borrowing base = (eligible A/R × A/R advance rate) + (eligible inventory × inventory advance rate) − reserves.
That borrowing base gives you the maximum senior debt the assets can support. From there, compare it against the proposed senior debt, the purchase price, and the equity cushion. This helps you see whether the deal stands on asset support or whether it leans too much on cash flow.
Check Whether the Asset Base Supports Purchase Price and Capital Structure
After you calculate adjusted collateral, put it next to the proposed senior debt and total purchase price.
Say adjusted collateral is $4,000,000 and proposed secured debt is $3,000,000. That means secured loan-to-value is 75%. If enterprise value is $10,000,000, then only 40% of the deal is backed by hard collateral. The rest depends on future cash flow holding up.
That’s the key read-through. You’re not just asking whether the lender gets comfortable. You’re asking whether the deal itself is built on solid ground.
For family offices, independent sponsors, and searchers, this comparison gets to a plain-English question: is the leverage justified by the structure, or is the deal asking too much from future earnings? If the asset base comes up short, you may need more equity, a seller note, or a lower purchase price to make the deal safer.
It helps to test debt capacity from both sides:
- Cash flow support
- Collateral support
If only one side works, the structure can get shaky fast.
Red Flags That Break Book Value Support
A business can show strong book value and still fail this test. Why? Because assets that are hard to verify or hard to pledge tend to shrink fast in a lender’s hands.
On the A/R side, pay close attention to balances aged past 90 days. Customer concentration can also cause trouble, since lenders may cap how much those receivables count in the borrowing base or apply reserves.
Inventory has its own weak spots. Obsolete or slow-moving SKUs are a problem. So are weak cycle-count records and custom inventory with little resale value. If the lender can’t see a clean path to liquidation, that inventory may not carry much weight.
Fixed assets can trip up a deal too. Equipment owned personally by the seller, or held in another entity, usually can’t be pledged unless it is cleanly transferred first. Existing UCC filings or hidden liens can block a new first-lien position. Deferred maintenance is another issue. It can push appraised liquidation value far below the amount shown on the fixed-asset register.
That’s why the early work matters. Run UCC searches, review fixed-asset schedules, and order third-party appraisals as soon as possible.
Conclusion: Use Book Value as an Input, Then Verify Every Major Asset Class
After the support test, one last issue remains: does the reported book value hold up once you check it? Book value is a starting point, not the finish line. It shows where value sits on the balance sheet. It does not tell you what those assets are worth today, what a lender will lend against them, or what you might get back in a wind-down.
That review begins with each major asset class. Receivables, inventory, PP&E, intangibles, and liabilities all need to be adjusted to collateral value. Then you match that result back to tangible equity.
In asset-based lending, the job is to turn reported book value into adjusted collateral value before you rely on it. For equipment and other fixed assets, use appraisals and orderly liquidation value instead of relying only on the fixed-asset register. And the haircut alone isn’t enough. The verification step matters just as much. Physical counts, on-site inspections, collateral reviews, and fresh AR aging reports are standard ways to catch stale records, missing assets, or inflated balances.
No single yardstick can do the whole job:
- Replacement cost shows what it would cost to rebuild the asset base.
- Fair value points to what the assets may fetch in an orderly market.
- Liquidation value gives you the downside test.
For equipment, orderly liquidation value often comes in at 60%–80% of fair market value, while forced liquidation value is often 40%–60%. If the adjusted collateral base does not comfortably support the proposed debt, the buyer should revisit the purchase price, use less leverage, or rework the capital stack.
Book value opens the deal review. Collateral verification is what decides whether it stands up.
FAQs
How do I adjust book value for underwriting?
Book value is assets minus liabilities on the balance sheet. But in asset-based acquisitions, that number often reflects depreciated historical cost, not what those assets are worth today.
That gap matters. A balance sheet can look clean on paper and still miss the mark once you dig in.
A good review usually includes a few basic checks:
- Write down stale assets, such as obsolete inventory and uncollectible receivables
- Adjust depreciated assets to fair market value
- Check for unrecorded liabilities
- Compare adjusted net asset value with normalized earnings to test underwriting
This is where the work shifts from simple accounting to judgment. For example, inventory may be listed at a value that made sense 18 months ago, but if it can't be sold now, that number isn't doing you any favors. The same goes for receivables: if customers aren't paying, those dollars shouldn't be treated like cash waiting to arrive.
Fixed assets need the same kind of scrutiny. A machine may be heavily depreciated on the books and still worth a solid amount in the market. Or it may be the opposite. That's why fair market value matters more than the carrying value when you're trying to figure out what you're buying.
Liabilities deserve the same hard look. Some don't show up neatly on the balance sheet right away, and those missing items can change the deal math fast. Once you adjust assets and liabilities, comparing net asset value with normalized earnings gives you a simple gut check. If the numbers don't line up, your underwriting may need another pass.
Which assets count as real collateral?
In asset-heavy businesses, book value can act as a floor for valuation. But that only works if you adjust the numbers to match fair market value.
In plain English, the balance sheet has to reflect what those assets and liabilities are worth today - not what they looked like years ago on paper.
That often means:
- writing down obsolete inventory
- checking whether receivables are actually collectible
- factoring in liabilities that haven’t been recorded yet
- using appraisals for machinery and real estate instead of old depreciated values
If you skip those adjustments, book value can give a false sense of security.
When does book value fail the deal test?
Book value stops being useful when it no longer matches the business you’re actually buying.
In asset-based acquisitions, that means going line by line through the balance sheet and fixing assets that are stale or priced too high. Common trouble spots include obsolete inventory and accounts receivable that likely won’t be collected. Those items should be written down to fair market value so the numbers reflect the deal in front of you, not an old accounting snapshot.
Depreciation deserves a close look too. A machine may still sit on the books at one value, while its market value tells a different story. If the depreciation schedule is out of step with current conditions, machinery values can mislead buyers during underwriting.
Clearly Acquired can help speed up this underwriting work with AI-native tools for financial normalization and deal analysis.
Related Reading
Find the right lender for your business
Whether it's working capital, an SBA loan, or acquisition financing — we'll match you with the right capital partner.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.