After You Buy a Business: 30-Day Handover Checklist
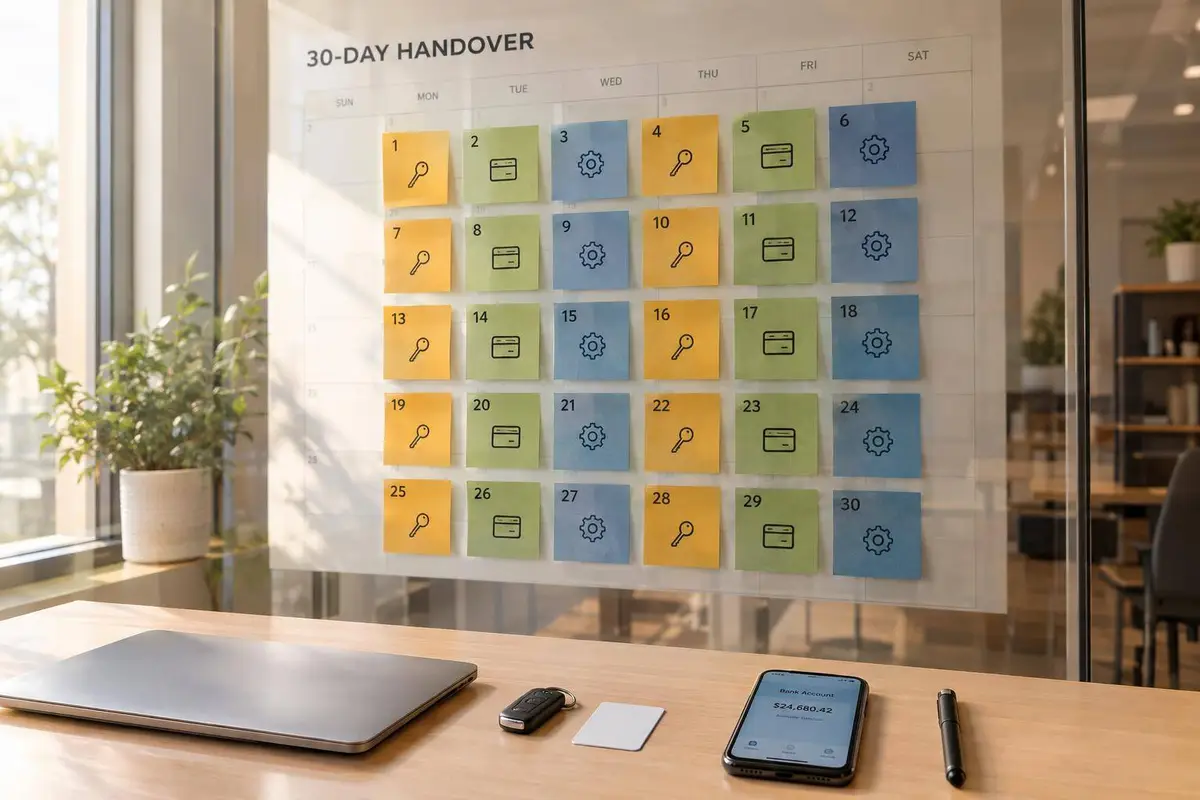
Closing is Day 0 — use a strict 30-day plan to secure access, cash, and operational continuity after buying a business.
 Samson JagorasPrincipal & CEO/CIOOctober 22, 2026
Find and close your next acquisition with expert backing
From sourcing to diligence to close — our buy-side team and platform help you win the right deal at the right price.
Buying a business doesn’t mean you control it yet. I treat closing as Day 0 and use the next 30 days to verify access, protect cash, and confirm the business can run without the seller.
My rule: give every task one owner, one deadline, and proof it’s done.
- Day 0: Collect signed documents, check purchased assets, confirm seller support, and set up secure records.
- Days 1–3: Verify banking, payroll, system access, insurance, licenses, and permits.
- Days 4–7: Meet employees, priority customers, vendors, and advisers. Confirm who can approve payments and other decisions.
- Days 8–14: Document and test daily work, review financial records, and address compliance gaps.
- Days 15–30: Reconcile accounts, review seller obligations, and sign a handover record that lists unfinished work.
- Days 31–90: Carry open tasks into the next plan, with owners and due dates.
Contract deadlines come first. I confirm required coverage and approvals at closing - not weeks later. And I treat Day 30 as <u>a status check, not a release of claims</u>.

Business Acquisition Handover: Day 0 to Day 90
The Complete Business Acquisition Process (Explained Step-by-Step)
sbb-itb-a3ef7c1
Days 1–3: Take Control of Finances and Access
Assign one escalation contact to each task. Mark unavailable banking, payroll, insurance, or critical systems Blocked and flag them as urgent. Contact the provider immediately, then bring in the seller, CPA, broker, SBA lender, or counsel as needed.
Seller-provided credentials are not proof of control. Update the Day 0 access register as you verify access. Track every blocked account, credential, or approval in the Day 0 issue log until control is confirmed.
Set Up Banking, Payments, and Payroll
Give the buyer or finance lead payment authority by Day 1. Complete verification by Day 3, or at closing if required. Confirm they can move money - not just view balances.
Create a separate row for each bank account or provider. Record the institution, account type, last four digits, current authorized users, required new users, approval limits, effective date, and verification owner. Check ACH, wire, positive-pay, check-signing, merchant-settlement, refund, and chargeback permissions.
Before the next payroll cutoff, verify the funding account, payroll frequency, next processing date, employee data, deductions, tax-deposit responsibilities, approval rights, timekeeping administrator, and backup administrator. Keep bank confirmations, permission records, payroll-provider acknowledgment, and evidence of a successful low-dollar payment test. Escalate blocked transfers immediately to the bank or processor, then to the seller, payroll provider, or counsel as appropriate.
Assign the CPA a separate Day 3 task: reconcile the prior three months of bank and credit-card activity against the general ledger, closing statements, and disclosed obligations. Record automatic debits, taxes, subscriptions, and debt service, including each amount, next withdrawal date, legal entity, and payment account. Flag seller-entity charges, duplicate subscriptions, and undisclosed obligations. Keep the signed review and open-item list.
Using a payroll provider does not remove the employer’s employment-tax responsibilities.
Once cash control is in place, move to system access and asset control.
Verify System Access, Keys, and Asset Records
Have the department lead create one row per system, account, key set, or titled asset.
Include accounting software, POS, CRM, scheduling, inventory, payroll, email, cloud storage, domains, websites, social-media accounts, payment platforms, security systems, keys, alarms, equipment records, and vehicle titles.
Test critical access by Day 1 and complete the remaining checks by Day 3. Confirm administrator rights through actual logins. Update recovery email addresses and phone numbers, change credentials, and enable multifactor authentication. NIST recommends limiting administrator privileges and removing access when circumstances change.
Keep login-test timestamps, permission confirmations, and signed asset receipts. Restrict seller access to what the purchase agreement or transition-services terms allow. Use named accounts, minimum permissions, activity logging, and expiration dates.
Log missing permissions immediately and escalate to the provider or seller. Involve counsel if asset ownership is disputed.
After verifying access, confirm the buyer can legally operate the business. This is a critical step for those who buy a business to ensure long-term compliance.
Check Insurance, Licenses, and Permits
Confirm required coverage and operating permissions at closing, verify them on Day 1, and obtain a broker or licensing review by Day 3. The buyer owns this go/no-go decision: affected operations must not continue without required coverage and approvals.
Check general liability, property, business-interruption, commercial auto, professional liability, cyber, workers’ compensation, and any industry-specific coverage for the buyer’s legal entity and operations. Obtain certificates of insurance, policy numbers, named-insured pages, limits, deductibles, exclusions, renewal dates, broker contacts, and claims information.
Verify workers’ compensation coverage before employees continue working where state law requires it. Confirm whether policies can be assigned or must be replaced at closing, and whether operating approvals are effective. Neither seller coverage nor a filing receipt establishes permission to operate.
Keep coverage confirmations, endorsements, and filing or approval receipts. Requirements vary by activity and jurisdiction, and an ownership change may require new registrations or approvals. If coverage or approval is uncertain, contact the broker, issuing agency, or counsel immediately before continuing affected operations.
Days 4–7: Introduce the Buyer to Key Contacts
Once access and control are secure, focus on the people and relationships that keep the business running.
Use four checklist blocks: Employees, Customers, Vendors, and Professional Advisers. For every entry, record the contact, seller attendee, buyer owner, meeting date, commitments, follow-up deadline, status, and notes. Address job security, payroll, benefits, authority, cancellations, supply interruptions, and assignment or change-of-control consents at closing or on Day 1 - not during this phase.
Employees: Confirm Roles and Staffing Needs
Employees checklist - HR lead; due Day 7. Hold a joint announcement and one-on-one meetings with critical employees. Meet the remaining employees as time allows. Use these conversations to check that the business can keep running without disruption.
Confirm each employee’s role, reporting line, duties, schedule, pay rate or salary, incentive compensation, benefits, tenure, accrued paid time off, employment classification, retention risk, and required training. Identify anyone whose departure could disrupt revenue or operations. Keep confidential HR matters out of group meetings.
Explain who owns the business, who employees report to, whether roles or schedules will change, how payroll and benefits will work, where employees can ask questions, and what to expect over the next 30–60 days. Don’t promise job security, pay increases, or unchanged benefits unless those commitments have been verified and approved.
Retain the updated roster, meeting notes, and onboarding acknowledgments. Report any pay, classification, or benefits discrepancies immediately to the buyer and the relevant advisers.
Customers and Vendors: Complete Priority Introductions
Customers checklist - department lead; priority introductions due Day 7. Protect revenue continuity by ranking accounts based on revenue concentration, renewal timing, open receivables, active projects, service risk, importance to business goals, and dependence on the seller. Start with the top 10–20 relationships, adjusting for business size and concentration risk.
Have the seller make the introduction and, where useful, endorse the buyer. Confirm service continuity, current orders or projects, contract and pricing status, open issues, renewal dates, decision-makers, and communication preferences. Keep introduction logs, acknowledged notices, and written commitments for both customers and vendors. Report threatened cancellations immediately to the buyer, and direct consent questions to counsel.
Vendors checklist - department lead; priority introductions due Day 7. Protect supply continuity by starting with suppliers whose interruption would halt operations. Confirm account contacts, the purchase-order process, pricing, payment terms, credit limits, ship dates, open orders, renewal dates, and notice requirements. Make clear who can place orders and approve changes.
Retain vendor records with the shared introduction documents. Immediately alert the buyer to threatened shipment holds, reduced credit, delayed deliveries, or required consent. Send unresolved assignment or change-of-control issues to counsel.
Advisers: Confirm Contacts and Decision Authority
Professional Advisers checklist - buyer; due Day 7. Confirm contacts for the lender and other financing contacts, the landlord or property manager, attorney, CPA or accounting firm, insurance broker or carrier, payroll provider, benefits adviser, and other specialized advisers as needed. For each, record contact information, scope, fees, communication protocol, open deliverables, and required approvals.
Create a signed authority matrix covering spending, bank payments, refunds, discounts, hiring, compensation changes, contract amendments, and customer credits. This review confirms the authority established earlier.
Pause disputed actions, preserve current practice when safe, and escalate conflicting instructions or unresolved lender requirements. Put off operating changes that aren’t needed while observing the business. Any introduction still incomplete on Day 7 needs a named owner, escalation contact, and firm completion date.
Record unresolved items in the issue log.
Get a Quality of Earnings analysis you can trust
Days 8–14: Document and Test Daily Work
With access and introductions complete, document how the business runs day to day.
The transition manager owns the Days 8–14 tracker. For each task, record the owner, deadline, evidence, result, and open issue. Accept only documents, permitted recordings, walkthroughs, or buyer sign-off as evidence.
Schedule critical demonstrations before the seller’s support window closes. Keep a session log with the date, attendees, topic, duration, materials received, open questions, and buyer approval of training. If a critical knowledge gap remains, send a written request before the contractual support period ends. Involve counsel if the seller refuses to meet an obligation under the agreement.
Start with the work that generates revenue and reveals gaps in daily work.
Document Revenue Workflows and Site Procedures
Department lead - due Day 14. Document five revenue-critical workflows: lead-to-sale, quoting and order entry, production or service delivery, invoicing and collections, and returns or warranty handling.
Each procedure needs an owner, inputs, steps, systems, approval limits, safety and quality checks, expected timing, an exception path, and a backup person.
Demonstrate, perform, verify: demonstrate the work, have buyer personnel complete it without prompting, then check their output. Test one normal transaction and one exception for each workflow. Keep the procedures, permitted recordings, test results, corrections, and buyer sign-offs.
Complete facility, equipment, vehicle, storage, and safety walkthroughs by Day 14. Locate shutoffs, emergency controls, maintenance schedules, and hazardous materials. Reconcile major assets to the purchase agreement or fixed-asset register, and record their condition, defects, and any missing keys, manuals, titles, or warranties. Keep photographs and completed walkthrough forms where permitted.
Leave failed tests open and schedule any remaining seller training before support ends.
Once the workflows are documented, check the numbers they produce.
Review Cash, Payroll, and Accounting
CPA - review due Day 14; review the first processed payroll. Review the chart of accounts, receivables and payables aging, inventory controls, cash reporting, bank and credit-card reconciliations, and close procedures.
Check payroll against employee records, time records, approved rates, deductions, and tax deposits. Keep reconciliations and payroll review records.
Classify financial exceptions as pre-close, post-close, or disputed under the purchase agreement. Log the amount, supporting evidence, responsible party, agreement clause, and deadline. Escalate unexplained balances or cash shortfalls to the buyer immediately, and involve counsel when contractual remedies may apply.
After the financial review, address unresolved legal items and gaps in daily work.
Review Compliance Gaps and Weekly Results
Transition manager - review due Day 14. Work with counsel or licensed advisers to check unresolved diligence findings, consents, IP assignments, domain ownership, tax registrations, assumed names, licenses, and required filings. Start urgent corrective action immediately. Keep filing receipts, approvals, and issue updates.
Begin weekly reviews of cash and the 13-week cash forecast, sales, customer retention, staffing, delivery, and compliance. Compare results with historical performance and acquisition assumptions. Keep source reports, meeting notes, decisions, owners, and deadlines.
Days 15–30: Confirm Completion and Record Open Items
Use the Days 8–14 logs to close remaining gaps, confirm buyer control, and gather final evidence.
Transition manager - by Day 15: Turn remaining targets into calendar dates measured from closing. Track contractual deadlines separately, and follow earlier notice deadlines. Mark a task complete only when buyer control, support, and evidence are documented.
Reconcile Financials and Review Seller Obligations
Use unresolved items from the issue log and weekly reviews to guide these checks.
CPA or controller - due by Day 30 or the earlier contractual deadline: Reconcile bank accounts, credit-card processors, sales deposits, accounts receivable, accounts payable, payroll, recurring charges, inventory, and the closing balance sheet. Prepare any working-capital or purchase-price adjustment calculation required by the agreement.
Keep bank statements, deposit reports, aged receivables and payables, payroll registers, invoices, receipts, reconciliation workpapers, and a written list of unresolved differences. Missing final data means the reconciliation stays open. Record what’s missing and when it must be delivered.
Attorney or deal lead - due by Day 15 or the earlier notice deadline: Maintain a post-closing obligations register covering escrow releases, earnout calculations and reporting, indemnification claims, seller-financed debt, transition services, noncompete or nonsolicitation obligations, required consents, tax filings, and other post-closing covenants.
For each item, record the responsible owner, contractual clause, notice period, required evidence, deadline, delivery method, and escalation route. Review proposed indemnification notices, earnout reports, or waiver language before delivery. Keep obligations that extend beyond Day 30 on the register, along with proof of transmission and receipt.
Sign and Archive the Day-30 Handover Record
Buyer and transition manager - due Day 30: Sign a dated status record covering:
- Banking and payment authority; payroll and accounting access; insurance, licenses, and permits; domains and software accounts; contracts; and titles and registrations.
- Required stakeholder introductions; documented operating workflows; archived financial and legal records; seller-support access; and open financial or compliance issues.
Treat every incomplete transfer as an exception - not a completed item. Give each exception an owner, action, due date, risk rating, and escalation route. Archive the signed record and supporting files in restricted, backed-up storage. Have counsel review any release or waiver language before signing.
Conclusion: Assign Open Items and Plan the Next 60 Days
Use the Day-30 record to move every remaining issue-log item into the next operating plan.
Buyer and transition manager - Day 30 review: Give every open item in the issue log and obligations register an owner, next action, deadline, and escalation contact. Confirm continuing seller support in writing where needed.
For Days 31–60, prioritize cash stability, unfinished transfers, and documentation gaps. For Days 61–90, schedule remaining seller obligations and any process, management, budget, integration, or growth items still open in those records.
Share a status summary with lenders and investors - not customer data or privileged legal advice. Cover financial reporting status, material exceptions, covenant or liquidity concerns, and expected resolution dates.
The Day-30 record confirms handover status only. It does not release claims or end obligations without a separate agreement.
FAQs
How does an asset versus stock purchase affect my handover?
For either purchase type, give each handover task a clear owner and deadline. Include governance documents, and make sure ownership details and records are accurate and up to date.
On Day 1, align buyer and seller messaging, brief managers, and hold an all-hands meeting supported by a written employee memo.
Then send weekly employee updates and contact customers and vendors early. During days 31–60, clarify roles and share early wins. During days 61–90, move to monthly updates and compare promises with results.
What if the seller stops helping before handover is complete?
Use the documented seller support scope and timeline to track any unfinished knowledge transfer. Your 30-day handover checklist should also cover account and system access, accurate customer and data transfers with least-privilege access, employee communications, and completion records - including governance and ownership updates.
Clearly Acquired can help organize the handover through its deal/transition platform.
How should I prioritize competing handover issues?
Focus first on keeping operations steady, making authority clear, and keeping people informed. Finalize governance documents, and securely transfer only the data needed to operate on Day 1. Keep access tightly controlled.
Hold a Day 1 all-hands meeting, share weekly employee updates, and reach out directly to top customers and vendors. Set clear expectations for seller support, including knowledge transfer, introductions, and help running the business. By Day 30, publish an updated organizational chart and decision-rights matrix.
Related Reading
Buy your next business with a full-stack team
Curated deal flow, Clara AI diligence, financing, and done-for-you advisory — all in one place.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.