Search Fund Timeline Planning: Ultimate Guide
Plan search fund timelines by dependencies, not dates — map phases, KPIs, diligence and financing checkpoints to avoid closing delays.
 Samson JagorasPrincipal & CEO/CIOAugust 25, 2026
Invest in profitable Main Street businesses
Create your investor profile to access curated deal flow, co-investment opportunities, and the Catalyst Fund.
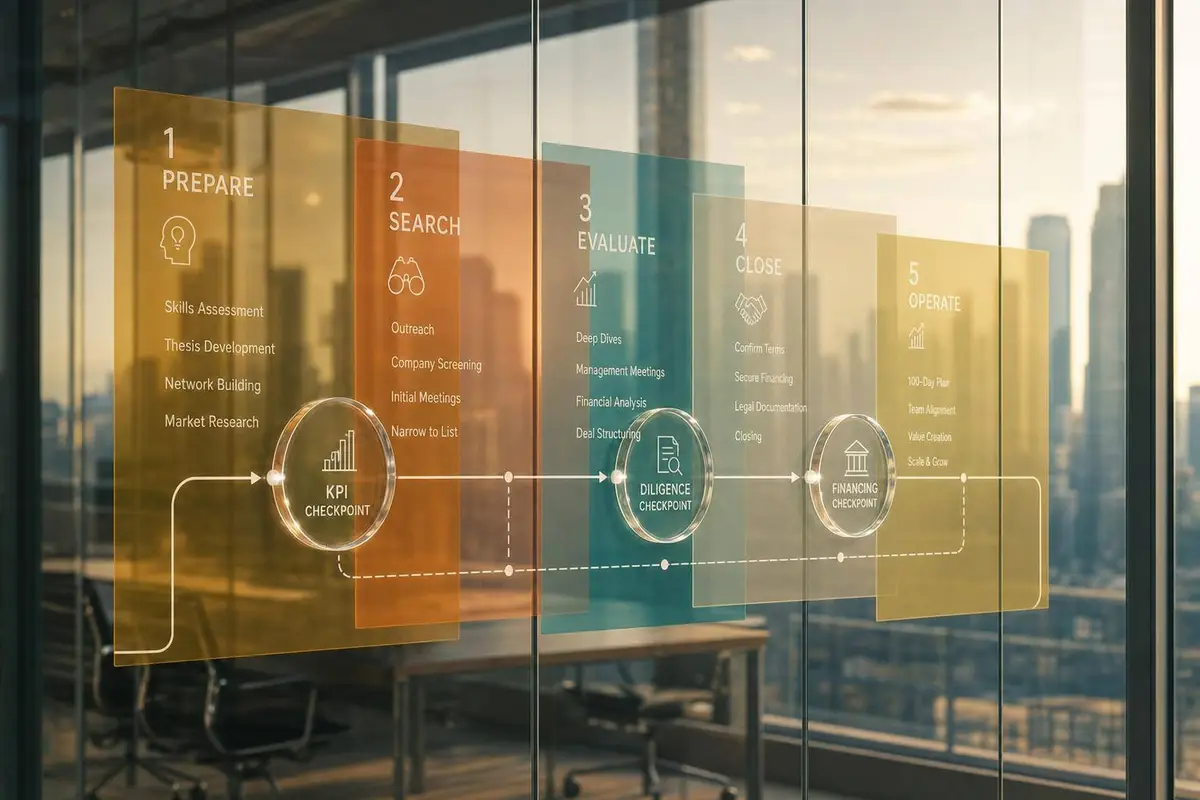
Most search fund delays come from one mistake: people plan by dates instead of dependencies. If I were planning a search fund on August 24, 2026, I’d build the timeline around gated phases, parallel workstreams, and hard checkpoints - not a loose calendar.
Here’s the short version:
- Formation and fundraise often take 3–6 months
- Search usually runs 12–24 months
- Acquisition often takes 3–9 months
- Ownership period is often 4–7 years
- Exit prep often starts 12–24 months before a sale or recap
And the numbers matter:
- Many searchers need to review 1,000–3,000 companies to close one deal
- They may need 5–15 LOIs
- Only 15%–25% of LOIs may get to close
- SBA 7(a) financing often takes 45–90 days
- Diligence for a deal can take 60–90 days
- Diligence costs can run $100,000–$300,000
If I wanted a clean plan, I’d focus on five things:
- lock the legal setup and buy box early
- track search KPIs every week
- start financing at the same time as diligence
- keep investors and lenders on a fixed update rhythm
- treat the first 100 days after close as part of the deal, not an afterthought
Quick comparison
| Phase | Common Time Range | Main Gate |
|---|---|---|
| Formation & fundraise | 3–6 months | Entity, docs, investor commitments |
| Search | 12–24 months | Pipeline, meetings, LOIs |
| Acquisition | 3–9 months | Diligence, debt, equity, close |
| Year 1 after close | First 12 months | Transition, reporting, lender tests |
| Exit path | 6–10 years | Sale or recap prep starts early |
The core idea is simple: I’d plan the search fund timeline like a staged execution plan, where each step clears the next one.
Building the Timeline: Formation, Fundraising, and Search
Pre-Fund Formation and Legal Setup
Use the 1–4 months before launch to lock in your search model, narrow your focus to 2–3 target industries, and make sure you have 18–24 months of personal runway in place.
Legal deliverables come first. Form the entity - most often a Delaware LP or LLC - and get the PPM, subscription agreements, and deck ready. Once that legal structure is in place, the next bottleneck is raising capital.
Then build the small group you'll lean on early: an M&A attorney with search fund experience, a CPA or accountant who can help with diligence, and a preferred SBA 7(a) lender. If you're planning to use SBA-backed financing, securing SBA funding before launch can save you from closing delays later.
Before outreach starts, lock your buy box. A common example is $1M–$3M EBITDA, margins above 10%, and recurring revenue. That kind of filter keeps the pipeline clean and stops you from wasting time on deals that were never a fit.
The setup work also includes your systems. Pick a CRM - Affinity, Folio, Salesforce, or HubSpot - set up email automation, and line up data sources like ZoomInfo or Apollo for outbound prospecting. At the same time, create a monthly or every-other-month investor update template so your communication stays steady from day one.
Search Capital Fundraising Milestones and KPIs
Set aside 4–6 months for fundraising, even if many raises close in 3–6 months. In practice, the process usually moves through four steps: finish the materials and legal docs, build a list of 40–60 target investors, run structured 30–45 minute meetings, and turn soft commitments into signed subscription agreements and wire transfers.
Start with the warmest investor relationships first. That early momentum matters more than people think, and it helps later conversations feel less like a cold start.
Here are the main KPIs to watch in this phase:
| KPI | Target Benchmark |
|---|---|
| Target investors identified | 40–60, tiered by likelihood to commit |
| Capital committed before final push | 60–70% of target |
| LP concentration | No single LP above 30% of the fund |
A traditional search fund usually raises $400,000–$600,000 from 10–20 investors, with unit sizes of $25,000–$50,000. Once you reach 60–70% of the target, the rest often comes together faster because investors can see others are already in. Put a firm deadline on the raise to keep decisions moving.
Search Phase Cadence, Pipeline Milestones, and Funnel Metrics
After the raise, the search phase usually runs 12–24 months, with a median of about 18–20 months. At that point, this stops being a story about ambition and starts being a numbers game. Activity has to stay steady, and qualification has to stay tight.
To close one acquisition, you may need to work through 1,000–3,000 prospects, generate 200–400 first conversations, and submit 5–15 LOIs. From there, only 15–25% of those LOIs typically make it to a close.
During the active search, target 15–25 new business contacts and 3–5 serious conversations each week. On a monthly basis, that usually means:
- 200–500 outbound emails
- 50–100 LinkedIn touches
- 2–4 site visits
A simple weekly rhythm helps. Use Monday and Tuesday for outbound work, Wednesday and Thursday for calls and diligence, and Friday for CRM cleanup and investor updates. Keeping 50–100 qualified leads in the pipeline lowers the odds of deal fatigue and makes it easier to walk away from a weak company.
Track the funnel as a chain of conversion rates, not just a pile of company names.
| Funnel Stage | Benchmark Conversion Rate | Volume Needed (for 1 Close) |
|---|---|---|
| Universe to Screened | 10–15% | 5,000–20,000 |
| Screened to Contacted | 75–100% | 400–1,000 |
| Contacted to Responded | 10–25% | 300–750 |
| Responded to NDA/CIM | 40–60% | 75–150 |
| NDA/CIM to Meeting | 30–50% | 30–75 |
| Meeting to LOI | 20–40% | 15–30 |
| LOI to Due Diligence | 50–70% | 5–10 |
| Due Diligence to Close | 40–60% | 2–3 |
Source: Aggregated from [4] and [2]
Check your pace at the 6-month and 12-month marks. If LOI volume is behind benchmark by month twelve, that's usually a sign that something is off: your sector focus may be too narrow, your outreach may not be landing, or your qualification rules may need to get tighter. Cut weak deals early. If a business has EBITDA margins below 10% or customer concentration above 25%, it should leave the funnel right away.
Those numbers shape the acquisition window, where diligence and financing need to move side by side.
Planning the Acquisition Window: LOI, Diligence, Financing, and Close
The acquisition window - from signed LOI to funded close - is where 30% to 50% of LOI-stage deals fall apart, most often because of diligence misses, financing slowdowns, or sellers dragging their feet. That’s why you need to build the schedule around the longest dependency, not the best-case scenario.
LOI Timing and Deal Process Design
Drafting and negotiating the LOI usually takes 2–6 weeks, and exclusivity often runs 60–120 days from signing. That may sound like a decent runway. In practice, it disappears fast once diligence, lender underwriting, and final approvals get moving.
As soon as the LOI is signed, start the data request, management meetings, and financing process right away. Don’t wait around. Before signing, do a deep red-flag review so you’re less likely to hit a nasty surprise late in the process.
Seller responsiveness can make or break the timeline. An organized seller can save you weeks. A messy one can add months.
Even after signing, keep backup deals warm in your pipeline. Staying active on 2–5 finalist opportunities while you're deep in diligence gives you room to move if the main deal stalls or starts to look different than expected.
Once exclusivity begins, the pace is mostly set by diligence speed, lender review, and third-party consents.
Diligence Workstreams and 60–90 Day Milestone Planning
For mid-market search fund acquisitions in the $2M–$10M enterprise value range, plan on a 60–90 day diligence window. In most cases, QoE is the item that sets the pace. It usually takes 3–6 weeks to finish, and lenders generally won’t complete underwriting without it. Professional diligence often costs $100,000 to $300,000.
Here are the usual timing anchors:
| Workstream | Typical Duration | Primary Dependency | What It Unblocks |
|---|---|---|---|
| Quality of Earnings (QoE) | 3–6 weeks | Seller financial data availability | Normalized EBITDA and add-back schedule |
| Legal diligence | 3–6 weeks | Contract and lease volume | Legal red-flag report |
| Environmental (Phase I) | 4–6 weeks | Third-party site access | Phase I report |
| Closing documents and consents | 2–4 weeks | Final purchase agreement and third-party consents | Signed purchase agreement and funds wire |
Set expectations early around data room completeness, then track open items every week. If documents are missing or questions sit unanswered, bring that into the open fast. Small gaps have a way of turning into closing delays at the worst time.
A delay in data delivery or QoE doesn’t just slow diligence. It pushes financing and closing further out too.
Debt, Equity, and Closing Timeline Dependencies
SBA 7(a) and 504 loan financing often sets the tempo, usually taking 45–90 days from application to funding, while conventional bank loans often close in 30–60 days. Since financing runs alongside diligence, get pre-qualified early. It cuts down uncertainty and lowers the odds of running past the exclusivity window.
On the equity side, traditional search fund investors usually have the right to invest 1.5x their search check in the acquisition round. Final commitment often hinges on a majority investor vote. A standard search fund capital stack is:
- 50–65% senior debt
- 25–40% equity from search investors
- 5–15% seller financing
The last 2–4 weeks usually go to finalizing the purchase agreement, working capital true-ups, and third-party consents like landlord consents, license transfers, and customer notifications. These are not side tasks. They sit right on the critical path to funding, so they need to be built into the close schedule from day one.
KPIs and Communication Rhythms for Investors and Lenders
Once diligence and financing run side by side, reporting turns into a timing tool. You need investors and lenders working off the same calendar so votes, funding, and closing conditions don’t slow the deal.
Because both tracks move at once, communication has to move on that same clock.
Search and Fundraise KPI Dashboard
Lead investor updates with numbers. Track runway, outreach volume, response rate, active deals, NDAs, management meetings, LOIs submitted, and LOIs signed. Add a dead-deal column so you can log why opportunities fell apart and tighten the buy box.
Use that dashboard to set the rhythm for investor updates. Each update should make three things easy to spot: progress, runway, and what needs a decision.
Investor Update Calendar From Launch Through Year One
Change the cadence based on the phase. If an LOI gets signed, or a deal dies during diligence, send a milestone update right away instead of waiting for the next planned send. After close, stay with monthly operating updates through the first year, then shift to quarterly reporting.
| Phase | Update Frequency | Key Metrics Reported | Major Decisions/Milestones |
|---|---|---|---|
| Fundraising | Bi-weekly during fundraising | Capital committed, units remaining, investor pipeline | Fund close, entity formation |
| Search | Monthly during search | Outreach volume, response rates, NDAs signed, management meetings | Pivot in thesis, budget extensions |
| Acquisition | Milestone-based | QoE findings, debt terms vs. other financing, equity commitments, diligence red flags | LOI signing, exclusivity, final go/no-go |
| Post-Close (Yr 1) | Monthly in Year 1 | Revenue vs. budget, EBITDA, debt service coverage, headcount | Key hires, CAPEX approvals |
| Post-Close (Yr 2+) | Quarterly after Year 1 | Long-term growth KPIs, board governance, exit readiness | Recapitalization, add-on acquisitions |
A good update doesn’t need to be long. It just needs to answer the obvious questions fast: What changed? How much runway is left? What decision is coming next?
Lender Milestones, Credit Committee Dates, and Closing Conditions
The same discipline applies to lenders. They work from fixed credit calendars, and they need a full package on time.
A complete lender package usually includes:
- Normalized financials
- Borrower information
- Financial projections
- Collateral detail
- Guarantor data
- QoE results
- Finalized purchase terms
Miss one item, and credit approval can slip.
Track three dates closely: package submission, credit approval, and funded close. Quality of Earnings reports usually take 3 to 6 weeks to finish. Third-party consents and final legal documents can add another 2 to 4 weeks after diligence and financing approval.
"The SBA loan timeline is the most common cause of closing delays. Start early."
As Mottalib Radif, Founder of SearchFundMarket, put it, that’s why financing needs to run in parallel with diligence if you want to stay inside a typical 60- to 120-day exclusivity window. Those dates don’t just affect closing. They also shape the handoff into the first 100 days after close.
Ready to Make Your Next Move?
Whether you're buying, selling, or investing — Clearly Acquired gives you the tools, data, and support to close with confidence.
Post-Close Timeline: First 100 Days, Year One, and Exit Planning
Closing the deal isn't the finish line. It's the handoff into the part that matters most: operating the business well. Once the money lands and ownership changes hands, the focus moves from getting the deal done to making the business run.
First 100 Days Transition Plan
Rule one: learn before you change. The first 100 days should be about earning trust, getting a clear view of how the company works, and showing the team that the business is steady.
A simple way to handle this period is to break it into three phases.
- Days 1–30: keep things stable. Hold an all-hands meeting, start the seller handoff, keep communication with customers and vendors steady, and watch cash flow every day.
- Days 31–60: shift into listening and diagnosis. Run weekly one-on-ones with the seller, talk with key employees, and begin post-closing working capital adjustments, which are usually finalized within 60 to 90 days of close.
- Days 61–100: move the seller into part-time support, lock in employee retention plans, and launch your KPI dashboard.
Your first priorities shouldn't come out of thin air. They should come straight from the diligence findings, lender conditions, and the seller transition plan.
A formal consulting agreement can help protect customer relationships and keep company know-how from walking out the door during the handoff. In most cases, you'll want the seller to stay involved for 6 to 12 months full-time or 12 to 24 months part-time.
By Day 100, the handoff phase should turn into a steady monthly operating rhythm, with regular reporting and a set board cadence.
Year One Operating Milestones and Board Rhythm
Year one is where you build discipline into the business. That usually means closing the books every month, hiring key people when needed, tracking budget versus actuals, reviewing pricing once, and checking lender covenants monthly. The reporting habits used during the deal for lender milestones and investor updates now become part of day-to-day ownership. For SBA 7(a)-financed acquisitions, keeping debt service coverage in line matters because falling short can create default risk.
Set up a board with 3 to 5 members, with a mix of investor representatives and independent directors, and meet for quarterly reviews. Those meetings should cover the numbers and the operating picture: revenue, EBITDA, cash flow, customer churn, backlog, and employee turnover.
What you track in year one doesn't just help you run the company now. It also becomes the baseline future buyers will examine. That's why clean reporting habits matter early. Exit prep usually starts in a formal way between years 4 and 6, but the groundwork starts much sooner with clean financials, less owner dependency, and more professional operations.
Conclusion: Build Search Fund Timelines Around Dependencies, Not Assumptions
At this stage, the whole timeline comes back to one simple test: did each dependency clear when it needed to?
Every part of a search fund - formation, fundraising, search, diligence, financing, close, and operations - depends on the part before it. If one piece slips, the next one usually does too. Searchers who close well and run the business well tend to be the ones who mapped those dependencies early, kept investors on a steady update schedule, and showed up on Day 1 with a written transition plan.
A disciplined timeline can improve close rates and give you a stronger base for an eventual exit. Map the dependencies, track the KPIs, and treat transition as part of the deal.
FAQs
Why plan by dependencies instead of dates?
Because search fund timelines change by stage and by how messy or simple the deal is. In most cases, the path looks like this: 3–6 months for fundraising, 12–24 months to find a target, 3–9 months to close, and then 4–7 years of operations before exit.
For planning, it helps to watch the milestones that actually move the search forward: outreach, conversion, and diligence. A common pace is 15–25 new contacts per week, 0.2%–0.5% closed-deal conversion, and 60–90 days for diligence. For more complex deals, diligence can stretch to 120 days.
That gives you a simple way to pressure-test your timeline. If outreach is slow, the search usually drags. If conversion is weak, you may need more deal flow at the top of the funnel. And if diligence keeps running long, that can push closing dates out by months.
What are the biggest causes of search fund timeline delays?
The two biggest reasons deals slow down are deal complexity and seller responsiveness. That tends to show up most during due diligence and closing, when small delays can stack up fast.
Most buyers should plan for a long timeline, not a quick sprint.
- Fundraising: 3–6 months
- Search: 12–24 months
- From LOI acceptance to close: 3–9 months
Inside the deal itself, the timeline usually looks like this:
- LOI drafting: 2–6 weeks
- Exclusivity: 60–120 days
- Due diligence: 45–120 days
- Financing: 30–90 days
- Closing: 2–4 weeks
That range is pretty normal. A simple deal with a responsive seller can move on the faster end. A messy deal, or a seller who’s slow to send documents and answer questions, can drag things out well past the original plan.
When should I start financing during an acquisition?
Start financing once you have a signed LOI. In most search fund acquisitions, financing happens in parallel with due diligence and usually takes 30 to 90 days. Diligence itself often lasts 45 to 120 days.
To keep things moving, many searchers get SBA pre-qualification early and line up lenders and advisors before a deal goes under LOI.
Related Reading
- The 2026 Stanford Search Fund Study
- SBA Loan Timeline: Step-by-Step Process
- Deal Structure Guide for Search Fund Business Buyers
- Search Fund Capital: Raising Bigger Rounds
- Form D Filing Deadlines for Search Funds
Sources & Further Reading
Get verified and access deal flow
Join our verified investor network and explore the Catalyst Fund — cash-flowing, uncorrelated Main Street assets.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.