Serial Acquisitions Face Antitrust Scrutiny
Stacked small acquisitions can trigger antitrust review when they concentrate local markets. Map deals and document standalone rationales.
 Samson JagorasPrincipal & CEO/CIOSeptember 25, 2026
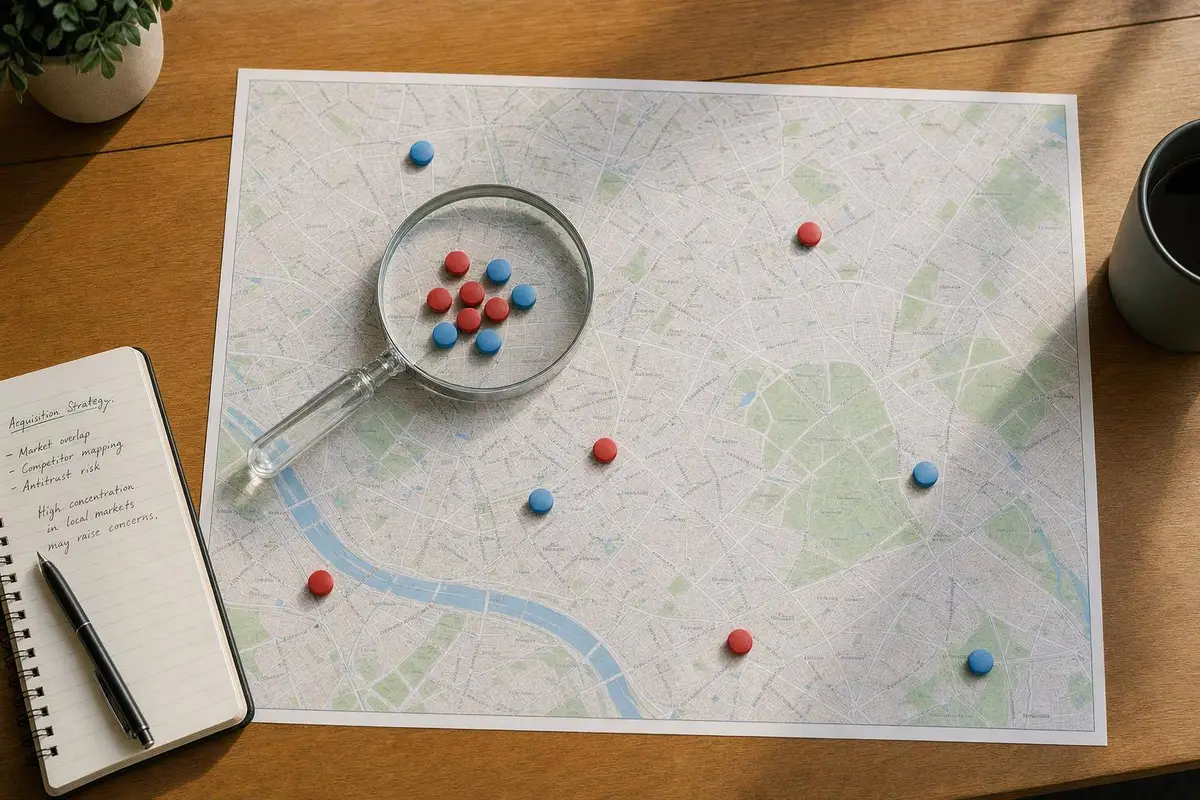
If you keep buying small companies in the same local market, antitrust risk can build fast - even when every deal is below HSR filing limits.
I’d sum it up this way: regulators are not just looking at one deal. They are looking at the pattern. A buyer with only a modest national share can still control 60% to 80% of a city’s service capacity, labor pool, or referral base after a string of add-ons.
Here’s the short version:
- Small deals can still get attention when they stack up in one metro, county, or service niche.
- The FTC and DOJ said in 2024 that roll-up activity is a focus, especially when firms use many sub-threshold deals.
- Local markets matter most, not top-line national share.
- Regulators often focus on local share, customer overlap, labor overlap, and internal deal documents.
- A later deal can put your earlier unreported deals under the microscope too.
- The cleanest path is to map past deals, test local overlap, and write a stand-alone reason for each acquisition before signing.
What I take from the article is simple: repeat buying needs repeatable antitrust review, especially in local service sectors like HVAC, dental, veterinary, healthcare, and route-based businesses.
Why serial acquisitions draw regulatory attention
Regulators look at more than one deal at a time. If a company keeps buying add-ons in the same area, agencies may ask whether those deals, taken together, reduce local competition. Antitrust law applies to deals that may substantially lessen competition, and regulators can review a serial acquisition program as a pattern instead of a bunch of separate, unrelated transactions.
Small deals are not always reviewed in isolation
The 2023 Merger Guidelines say this directly: multiple acquisitions in the same market, or in closely related markets, may be reviewed together for their cumulative competitive effects. The FTC and DOJ doubled down on that point in a joint 2024 public inquiry into serial acquisitions and roll-up strategies.
A clear example is the FTC’s September 2023 lawsuit against U.S. Anesthesia Partners and its sponsor, Welsh, Carson, Anderson & Stowe. The agency alleged a decade-long Texas anesthesia roll-up that consolidated over a dozen practices.
So what happens next? Regulators often move past the details of each deal and look at the buyer’s overall footprint. In plain English, they want to know whether the filings add up to a larger roll-up plan.
Roll-ups can reshape local competition faster than national data shows
National market-share data doesn’t always tell the full story. A buyer can have a modest national share and still control 60% to 80% of a metro area’s service capacity.
That matters a lot in local service sectors like HVAC, dental, veterinary care, and route-based businesses. People usually buy these services close to home. So when a roll-up acquires several leading providers in the same city or region, pricing, referral patterns, and customer choice can shift fast - often much faster than national data would suggest.
| Market Scope | What Agencies Examine | Why It Matters |
|---|---|---|
| National | Overall revenue share | Can miss local concentration |
| Local (MSA, county, zip-code cluster) | Combined capacity, rival count, customer options | Reflects actual competitive conditions |
| Labor market | Overlap in specialized staff or physicians | Can signal wage suppression risk |
Those local signals - share, overlap, and labor concentration - tend to shape the next round of review. That’s why regulators focus on local share, customer overlap, and labor overlap, not just the headline size of a deal.
sbb-itb-a3ef7c1
What regulators look for in repeat-buyer patterns

Serial Acquisition Antitrust Risk: Higher-Risk Patterns vs. Cleaner Practices
Local market share, customer overlap, and labor overlap
Once a buyer starts doing repeat deals in the same market, regulators usually zero in on three things: share, overlap, and documents.
At the review stage, agencies look at the buyer’s combined footprint at the local level. The basic question is simple: after the deal closes, how many independent options are still left for customers and workers?
Before signing, it helps to size up three risk areas:
- Local share
- Customer overlap
- Labor concentration, such as the share of licensed HVAC technicians or registered nurses within a 45-minute commute of a metro area
The 2023 Merger Guidelines also treat labor markets as relevant. That means a roll-up can face scrutiny even when product share does not look especially high.
Evidence of a broader roll-up plan
Internal documents often shape serial-acquisition review. Agencies put a lot of weight on contemporaneous materials like investor decks, lender memos, board presentations, and integration plans. They use those records to decide whether the buyer is carrying out a deliberate consolidation strategy or just making separate, stand-alone deals.
Word choice matters more than many buyers expect. Documents that talk about controlling rate cards, becoming the only scaled platform in a region, or lining up acquisitions to capture most competitors in one city are exactly the kind of material regulators flag. And if the documents point in different directions, that can make things worse. Agencies tend to read the full acquisition history together, not one file at a time.
Higher-risk patterns vs. cleaner facts: a side-by-side comparison
| Factor | Higher-Risk Pattern | Cleaner Practice |
|---|---|---|
| Geographic concentration | Multiple add-ons in the same city or county within a short window | Acquisitions dispersed across different metros or commuting zones |
| Local market share | Combined portfolio reaches a high share of local revenue or capacity | Each deal leaves multiple independent rivals intact in the local market |
| Customer overlap | Same accounts, referral channels, or routes served by two or more portfolio companies | Distinct customer bases with documented alternatives remaining post-close |
| Labor-market overlap | Portfolio becomes dominant employer for a specialized role in one commuting zone | Broad hiring pool; integration plan expands rather than reduces worker options |
| Internal documents | Decks describing plans to eliminate rivals or consolidate the market | Deal-specific memos focused on capabilities, service quality, and geographic fit |
| Post-close integration | Rapid facility closures and brand consolidation that remove independent competitors | Operational independence maintained in high-share markets |
When a pattern hits several of the left-column markers at once - same geography, growing share, overlapping labor pools, and hard-charging internal language - the risk starts to stack up. That kind of mix is much tougher to defend than any one factor on its own.
If several of these signals show up together, the answer is usually a cleaner deal structure, not just cleaner paperwork.
How sponsors and searchers can structure cleaner deals
Knowing what regulators watch is only part of the job. The other part is much more practical: build habits that cut avoidable risk before a deal lands on a regulator’s desk. In roll-ups, many antitrust issues aren’t unavoidable. They come from weak planning and from saying too much in emails, decks, and memos.
Assess cumulative risk before signing
Build an acquisition map before signing any LOI. Catalog prior and pending deals by geography, service line, customer type, and labor pool. Then place the new target’s footprint on top of that map.
Start with local concentration. National share can hide the problem. A business may look fine at the country level while one metro area is getting crowded fast. Tie the map to the three red flags from the prior section: share, customer overlap, and labor overlap.
It also helps to set internal stop signs early. Put triggers in place for share, competitor count, and deal pace. If one of those triggers is hit, pause approval until antitrust review is done. A centralized deal system makes this much easier because it can flag overlap early and keep the underwriting view in sync across the team.
Once the map is clear, write the business case for each target before diligence starts.
Document a standalone business rationale for each deal
After checking concentration, the next step is simple: explain why the deal stands on its own.
Every add-on should have a written reason for existing even if no other acquisitions ever happen. That reason might be succession continuity, access to a new customer segment, a specialized certification, or entry into a nearby geography where several competitors still remain. The key point is straightforward: each deal needs to make sense by itself.
Language matters here. Use neutral wording in emails, decks, and lender memos. Avoid phrases like "lock up", "take out", or "dominate a local labor market." Those words can come back to haunt you. A better approach is to describe synergies as customer or operating gains, not as a way to close off the market.
Use transaction hygiene to avoid self-inflicted problems
Once the rationale is set, keep every document lined up with it. Use one written deal thesis across CIMs, lender memos, and diligence notes. That same thesis should guide what goes to outside counsel, lenders, and co-investors. Put bluntly, you don’t want the language a regulator could use as evidence showing up anywhere in those materials.
Timing matters too. If a metro area is getting close to concentration limits, space deals out, vary the type of acquisitions, or shift to nearby markets. Sometimes the cleanest move is not to force one more deal into a crowded area.
A centralized deal platform can help keep one version of the deal story across sourcing, diligence, and close.
Ready to Make Your Next Move?
Whether you're buying, selling, or investing — Clearly Acquired gives you the tools, data, and support to close with confidence.
Conclusion: A repeatable acquisition strategy needs repeatable compliance
Those controls matter because regulators look at the full buying pattern, not just one deal at a time. A string of acquisitions can draw antitrust review even when no single deal looks all that big. The DOJ and FTC may assess repeated acquisitions together when they make up a pattern in the same or related markets. The point is plain: a run of small deals can still bring enforcement, even if no one transaction jumps off the page. And the risk is usually measured in local concentration, not national market share.
Key takeaways for buyers, sponsors, and investors
The message is straightforward.
Small deals can still carry serious risk when they add up to a pattern. The FTC said in 2024 that roll-up strategies can let firms build significant market control without government scrutiny when individual deals fall below reporting thresholds. That assumption is no longer safe.
Local market effects drive the review. Regulators focus on what happens to competition in a given metro area, ZIP code, or customer niche, not just across the country.
Market mapping, a deal-specific rationale, and clean deal documents and consistent messaging help support the case. Investors more often want serial buyers to show that work before they commit capital, not after a problem appears.
Repeat buyers avoid antitrust surprises by building compliance into the acquisition process, not treating it as a filing-stage fix.
FAQs
Why can small acquisitions still trigger antitrust scrutiny?
Regulators look at competitive effects in the aggregate, not only through the lens of one deal’s size. That matters in roll-up strategies, where a string of smaller acquisitions can slowly concentrate local market share, especially in fragmented industries.
There’s also repeat-buyer risk. Each new deal can shrink the field of rivals, push prices up, or take out a separate competitive check in the market. Sponsors and searchers can put together cleaner transactions by reviewing market share, local overlap, and filing defensibility early.
How do regulators define a local market in roll-up deals?
In roll-up deals, regulators don’t just look at each acquisition one by one. They look at competition in a specific geographic area or niche market and ask a simple question: what happens when you add these deals together?
That matters because even small acquisitions can get attention if, taken as a group, they substantially lessen competition.
They’re also watching for a few clear signals:
- Growing local market share
- Repeat buyer patterns
- Deal structures that seem designed to stay below HSR reporting thresholds
In plain terms, a buyer can’t assume a deal is safe just because each purchase looks small on its own. The pattern behind the deals matters too.
What should buyers review before signing another add-on?
Before signing another add-on, buyers should look at antitrust risk across the entire roll-up pattern, not just the deal sitting in front of them. A string of small acquisitions can still draw attention if it chips away at local competition, even when each deal falls below HSR reporting thresholds.
That’s the part people sometimes miss. A deal can look small on paper and still matter a lot in a local market. If the same buyer keeps picking up nearby competitors, regulators may look at the pattern, not just the price tag on one transaction.
On the diligence side, keep the basics tight:
- Clear financial records
- Documented processes
- A defensible deal thesis
- QofE work that supports normalized EBITDA and add-backs
Also, stay away from deal structuring that looks like it was set up to remain under HSR thresholds. That can create its own problems fast.
Related Reading
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.