Seller Note Security by Deal Type
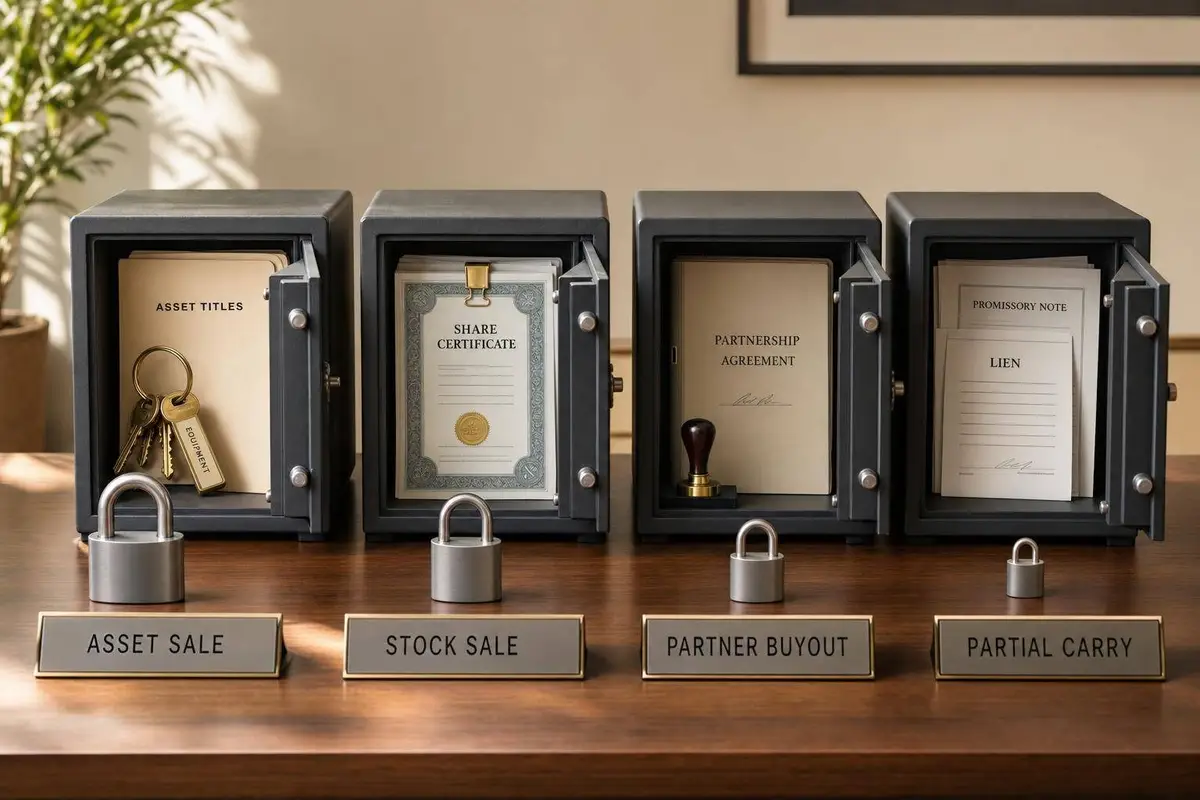
Asset purchases usually give the seller the strongest backup, stock deals come next, and partial carry or standby notes often leave the seller leaning on note terms more than property.
 Samson JagorasPrincipal & CEO/CIOJuly 29, 2026
Get matched with the right lender for your business
Compare offers from our vetted network. Pre-qualify in minutes — no impact to your credit.
If I had to sum it up in one line: asset purchases usually give the seller the strongest backup, stock deals come next, and partial carry or standby notes often leave the seller leaning on note terms more than property.
If you’re checking how safe a seller note is, I’d look at one thing first: what can the seller take if the buyer stops paying? That answer changes by deal type.
Here’s the short version:
- Asset purchase: the seller can often take a lien on named assets like equipment, inventory, receivables, and IP.
- Stock purchase: the seller usually gets a pledge of the shares or LLC interests, not a lien on each company asset.
- Partner buyout / internal transition: often uses the same equity pledge, but control rules, transfer limits, and lender consent can narrow the seller’s rights.
- Partial seller carry / standby / forgivable note: the seller is often junior to a bank, so protection comes more from the note terms, payment triggers, and any intercreditor limits.
A simple rule I use: the more direct the seller’s claim to named assets, the lower the recovery risk tends to be. By contrast, when the seller only holds pledged equity or waits behind senior debt, recovery can drop fast if the business value slips.

What Serves as Collateral for the Seller Financing in a Business Purchase? How to Buy a Business

Quick Comparison
| Deal type | Main security tool | What the seller can reach | Main risk in default |
|---|---|---|---|
| Asset purchase | Security agreement + UCC-1 | Specific business assets | Assets may be worth less than expected |
| Stock purchase | Stock or membership interest pledge | Equity interest | Equity may have little value or transfer limits |
| Partner buyout / internal transition | Equity pledge, sometimes guaranty or limited lien | Owner stake, sometimes extra support | Ownership rules and lender limits can block recovery |
| Partial carry / standby / forgivable note | Note terms, subordination terms, milestone rules | Often little or no direct collateral | Seller may sit behind senior debt and wait for payment triggers |
About 9 in 10 U.S. businesses are small businesses, and many sale deals include some form of seller financing. That makes lien position, transfer limits, and default rights more than paperwork — they shape whether the seller can collect or not.
If I were reviewing a deal, I’d want to know where the seller sits in the lien stack, what collateral is pledged, and what happens on default before closing day.
1. Asset Purchase Transactions
In an asset purchase, the buyer takes specific business assets instead of the whole company shell. For seller note security, that often gives the seller a pretty direct path: the seller can take a security interest in the assets being sold, such as equipment, inventory, receivables, and intellectual property.
The main documents are a security agreement and a UCC-1 financing statement filed with the right state filing office to perfect the lien. If the buyer defaults, the seller can accelerate the note and enforce the lien. That said, recovery still comes down to what those assets are worth at the time of default.
Asset purchases usually give the seller the clearest collateral path because the pledged assets are defined at closing. In plain English, the seller knows what sits behind the note. That collateral position gets less clean in a stock purchase, where the collateral is not tied to separately sold assets.
2. Stock Purchase Transactions
In a stock purchase, the buyer takes the company equity, not a menu of assets. That changes the collateral setup in a big way. The seller usually can’t put a lien on equipment, inventory, or receivables tied to the sale itself. Instead, the seller’s collateral is the ownership interest the buyer just acquired.
That’s why these deals usually use a Stock Pledge Agreement — or a Membership Interest Pledge Agreement if the business is an LLC. Under that setup, the buyer pledges the acquired shares or membership interests back to the seller as collateral for the note.
If the buyer defaults, the seller can foreclose on that pledged equity interest. Put simply, the seller’s recovery turns on the value of the equity and whether that interest can be transferred. Buyers often secure these deals by working with a lender network to ensure the capital structure supports the pledge. In a stock deal, the pledge reaches the equity itself, not the company’s individual assets.
| Factor | Asset Purchase | Stock Purchase |
|---|---|---|
| Collateral type | Direct lien on specific assets | Pledge of shares or membership interests |
| Default remedy | Repossess/foreclose on assets | Foreclose on the pledged equity interest |
| Collateral reached | The sold assets | The ownership interest in the business |
You’ll often see this same equity-pledge setup in partner buyouts and internal transitions. In those cases, the pledged interest is tied to the departing owner’s stake.
3. Partner Buyouts and Internal Transitions
Partner buyouts and internal transitions often look a lot like stock purchase collateral. But there’s a twist: the pledge is shaped by control rights, transfer limits, and any lender approval the deal may need.
In many cases, these deals use the same equity-pledge setup as stock purchases. The difference is that there’s usually more back-and-forth over who stays in control during the handoff.
Common protections include:
- a pledge of the departing owner’s shares or membership interest
- transfer restrictions
- when permitted, a lien on business assets or a guaranty from the continuing owner
Existing debt and ownership agreements often limit how much collateral the seller can take.
Unlike outside sales, internal transitions tend to offer fewer collateral choices. The reason is pretty simple: the focus is on continuity, not a clean transfer of all business assets. So collateral is usually driven by the ownership agreement and current debt terms, not by a brand-new negotiation.
That shifts the deal. Internal transitions are usually less about taking as much collateral as possible and more about balancing security with business continuity.
4. Partial Seller Carry, Standby, and Forgivable Note Structures
These setups move security away from hard collateral and put the weight on payment terms, timing, and repayment rules. Unlike asset purchases, where the seller may hold a lien on specific assets, partial carry, standby, and forgivable notes usually depend less on pledged property and more on how the note is drafted.
With a partial seller carry, the seller finances only part of the purchase price. In many cases, that note sits behind a senior lender. That junior position limits what collateral the seller can realistically claim. Senior lenders often restrict junior lienholders from taking security interests in the same assets, so the seller’s protection usually comes from the repayment schedule, the interest rate, and any intercreditor agreement that controls when payments can be made.
Standby notes push this even further. In a standby setup, the seller agrees not to receive payments, or to defer them, until the senior debt is paid down to a set level or the business reaches defined performance thresholds. In that case, collateral matters less. The seller is relying on the trigger itself: payments start again only when the business can support them.
Forgivable notes work a bit differently. The principal balance goes down if the buyer hits specific milestones, like revenue targets or employee retention requirements. Instead of collateral, these notes lean on performance-based terms. The seller accepts conditional repayment in exchange for an easier transition or a higher stated purchase price.
Across all three, seller protection comes more from the note terms than from pledged assets. So the main issue isn’t asset recovery. It’s how much principal is still on the line.
Pros and Cons of Each Deal Structure for Seller Note Security
When you line these deal structures up side by side, a pretty clear pecking order appears. It comes down to one thing: can the seller claim specific business assets, only an ownership stake, or mostly just rely on the payment terms in the note?
Asset purchases are at the top of the list for seller protection. In this setup, the seller can place a direct lien on the exact assets being sold, such as equipment, inventory, receivables, and intellectual property, and perfect that lien with a UCC-1 filing. If the buyer defaults, the seller isn’t left guessing what backs the note. There is a known pool of assets to go after. That’s why asset purchases are usually the strongest setup for seller note security.
Stock purchases and partner buyouts are a step down. Here, the seller usually gets an equity pledge instead of a lien on the company’s assets. Put simply, the collateral is the ownership interest the buyer acquired, not the business property itself. That can get messy fast. If the buyer defaults, recovery depends on whether that equity still has any value and whether it can even be transferred. With partner buyouts, things can get even tighter because transfer limits, control rights, and lender approvals may shrink what the seller can take as collateral.
Partial seller carry, standby, and forgivable notes give the seller the weakest hard collateral position. In most cases, the seller is behind a senior lender, which limits junior lien rights. So the seller is leaning less on pledged property and more on the wording of the deal itself. Protection usually comes from payment terms, intercreditor agreements, and milestone triggers. The seller’s risk turns on how much principal is still unpaid and whether the repayment conditions are ever satisfied.
Conclusion
Seller note security isn’t standardized. It changes with the shape of the deal.
In an asset sale, the seller may take a direct lien on the business assets. In a stock sale, the collateral often shifts from the assets to the equity itself. In a partner buyout, personal or corporate guaranties may come into play when allowed. And with partial carry or standby notes, the seller is often behind senior lenders in lien priority.
Before anyone signs, both sides should make sure the security tool fits the legal structure of the deal. They should also confirm exactly where the seller stands in the lien stack.
Before closing, the collateral setup should fit the deal structure.
FAQs
How do I know what collateral a seller note actually has?
Check the deal documents to see what collateral secures the seller note. That depends on how the deal is set up, so read the security terms with care.
At a basic level, the note should say whether it’s secured and spell out what backs it, such as assets, stock, or ownership interests.
What makes an equity pledge riskier than a lien on assets?
An equity pledge is usually riskier because its value rises or falls with the company’s overall performance and whatever equity value is left. And that can shift fast.
A lien on assets is often more direct. It’s tied to specific business assets, not the ownership stake itself.
Can a seller still be protected if the note is junior to bank debt?
Yes. A seller can still have protection even if the note sits behind bank debt.
The exact level of protection depends on how the deal is set up and which security tools are available in that deal.
Find the right lender for your business
Whether it's working capital, an SBA loan, or acquisition financing — we'll match you with the right capital partner.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.