Retention Bonus in Business Sales: Amounts and Terms
Closing, staged, milestone, and deferred retention bonuses compared: typical amounts, timelines, vesting rules, and who pays in Main Street and lower-middle-market deals.
 Samson JagorasPrincipal & CEO/CIOAugust 17, 2026
Sell your business for maximum value
Our sell-side advisors package, market, and negotiate your exit to qualified, verified buyers — confidentially.
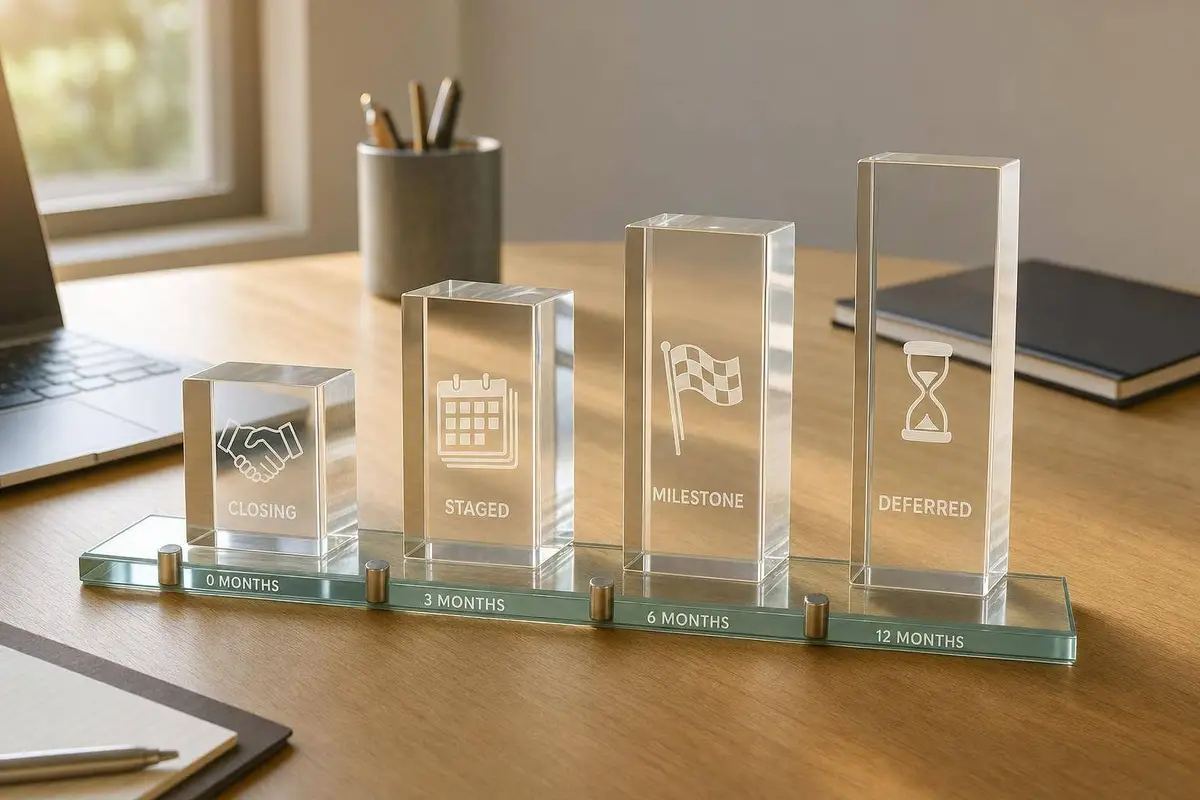
If you need someone to stay after a business sale, the bonus has to match the job and the timeline. In most Main Street and lower-middle-market deals, retention bonuses land around 15% to 30% of base salary, but they can run much higher for a seller-operator or a hard-to-replace manager. The four main setups are simple: pay at close, pay in tranches, pay for milestones, or pay over multiple years.
Here’s the short version:
- Closing bonus: best when you only need the person there through closing
- Staged stay bonus: best for a 6- to 18-month handoff
- Milestone bonus: best when payout should depend on results
- Deferred multi-year plan: best when you need continuity for 2 to 5 years
A few numbers stand out fast:
- Key employee bonuses often fall in the 10% to 50% range of base salary
- Staged and deferred plans can reach 50% to 150% for top leaders
- In small deals, seller-owner retention pay may land around $25,000 to $150,000
- In SBA-backed deals, a common setup is $10,000 to $25,000 at close plus a 12-month stay payment
The core tradeoff is simple: the more time or performance you ask for, the more money, tracking, and legal detail you usually need. Professional consultation services can help structure these agreements to protect both parties.

Retention Bonus Structures in Business Sales: At-a-Glance Comparison
Retention Bonuses Explained: What Founders Should Consider Before Using Them
sbb-itb-a3ef7c1
Quick Comparison
| Structure | Typical Pay | When It’s Paid | Best Use |
|---|---|---|---|
| Simple cash closing bonus | 10% to 30% of base salary, sometimes more | At closing or soon after | Keep people in place until the sale closes |
| Cash stay bonus with staged tranches | 20% to 40%, sometimes higher | Over 6 to 24 months | Hold key staff during the handoff |
| Milestone-based retention bonus | Often 30% to 60% | When set targets are met | Link pay to staying and hitting goals |
| Deferred multi-year retention plan | Often 50% to 100%+ total | Over 2 to 5 years | Keep leaders in place for longer-term transition |
If I were framing this for a buyer or seller, I’d keep it this plain: use the lightest structure that still covers the risk after closing.
1. Simple Cash Closing Bonus
Bonus size
A simple cash closing bonus is usually set at 10%–50% of an employee's annual base salary. In many Main Street deals, 20%–30% is common for key roles. So if someone earns $110,000 per year, the bonus often lands around $22,000–$33,000. In smaller deals, that number can climb to 50%–100% of base salary when the buyer is leaning heavily on that person to help with the transition.
Looking at it from the deal side, simple closing bonuses for non-owner executives often fall in the 0.25%–1.0% of enterprise value range. On a $10 million deal, that usually means about $25,000–$100,000. What drives the amount? Mostly two things: how hard the person would be to replace, and how much the buyer needs that person to help get the deal over the finish line. This is the shortest-horizon option in the group.
Payout timing
The main draw here is speed. The payment is usually made at closing or within 3–10 business days after the deal funds. In plenty of transactions, the bonus is listed right in the closing statement, next to seller proceeds and advisory fees. In smaller Main Street deals, the seller often pays it straight from sale proceeds as a way to reward loyalty and help the handoff go smoothly.
Vesting conditions
The rule is pretty simple: the employee must still be employed when the deal closes. If they quit before closing, or if they are terminated for cause, they lose the bonus. There is usually no long vesting schedule, no performance hurdle, and no clawback period. If the deal closes and the employee is still there, the payment is generally earned.
Deal fit
This setup works best when the buyer wants a clean handoff, not a long retention period. It makes sense in smaller owner-operated businesses where a few people - like a general manager, controller, or lead salesperson - can have a big effect on whether closing feels smooth or messy.
The weak spot is easy to see. If the buyer needs someone to stay for 12 months or more, a one-time payment at closing may not do the job. Say the GM is the only person who fully knows the customer base or the way a core system runs. In that case, a single check at closing may not be enough to keep them around through integration. A staged stay bonus or a deferred multi-year plan is often the better move. If post-close retention matters, staged tranches are usually the next step.
2. Cash Stay Bonus with Staged Tranches
When the focus moves from getting the deal closed to keeping people in place after closing, the payment plan needs to last longer. That’s where a staged cash stay bonus comes in.
Instead of paying the full amount at close, the buyer breaks the bonus into two or three cash payments over time. The idea is simple: give key employees a reason to stay through the integration period, not just through signing day.
Bonus size
In Main Street deals (sub-$5 million enterprise value), staged stay bonuses for key managers usually land in the 10%–30% of annual base salary range. For people in critical or hard-to-replace roles, that can climb to 40%–50%.
In lower-middle-market transactions ($5 million–$50 million), packages for top managers tend to fall between 30%–100% of annual base salary. Senior executive retention pools often reach 1%–3% of enterprise value, and individual packages frequently equal 0.25x–1x annual cash compensation, paid out over 12–36 months.
Put plainly, the bonus has to be big enough to shape behavior. If it’s too small, it doesn’t do much beyond sending a message.
Payout timing
Most plans split the bonus into two or three tranches. Common setups include:
- 50/50
- 40/30/30
Payments may start at closing, then continue at 6, 12, 18, and sometimes 24 or 36 months. In many cases, buyers pay only part of the total upfront and hold back the rest. A common holdback is 25%–50% of the full amount.
Vesting conditions
Each payment usually depends on continuous, satisfactory employment through the date that tranche is due.
Most agreements follow a simple stay-or-forfeit approach. If the employee quits or is terminated for cause, any unpaid tranches are lost. If the buyer removes the role or terminates the employee without cause, many agreements allow acceleration or continued payout.
For Main Street deals, simpler is better. Advisors often suggest using one or two clear, auditable conditions per tranche, not a long checklist of KPIs.
Deal fit
This setup makes sense when the buyer needs stability long enough to complete a handoff, put systems in place, or steady day-to-day operations. It sits in the middle ground between a one-time closing bonus and a long deferred plan.
It tends to work well when the seller-founder still runs much of the business, when the company relies on specialized processes that need to be documented, or when the buyer needs management continuity during a system rollout like a CRM or ERP.
If the buyer also wants pay tied to clear, measurable results, a milestone-based bonus is usually the better match.
3. Milestone-Based Retention Bonus
If a stay bonus isn't enough, tie part of the payout to operating results. A milestone-based bonus works best when payment should follow results, not just time in the role. That shifts the focus from simple retention to retention plus value creation.
Bonus size
Set the bonus based on how important the target is and how much influence the person has over hitting it.
Payout timing
Pay only when the contract-defined target is met. Common targets include revenue, EBITDA, customer retention rates, or handoff milestones as part of the post-acquisition workflow. The agreement should spell out the metric, the measurement source, and the payout trigger. If those details are fuzzy, trouble tends to show up later.
Vesting conditions
Payment depends on hitting the metric, not just staying employed. That's why the metric definitions and measurement terms are some of the most important parts of the agreement. If the target can be read two ways, people usually will read it two ways.
Deal fit
This setup fits high-growth, turnaround, or negotiation-gap deals where part of the deal's value depends on post-close execution. The tradeoff is pretty plain: stronger alignment, but no payout if targets are missed, plus more room for measurement disputes. When both time and performance matter, the deferred multi-year plan is the next step.
4. Deferred Multi-Year Retention Plan
Use a deferred multi-year plan when the buyer needs people to stay for years after closing, not just through the handoff. Compared with a short stay bonus, this setup buys more time. The flip side is simple: more admin, more tracking, and more room for disputes.
Bonus size
These bonuses are usually bigger than a one-time closing bonus or a short-term stay bonus because the buyer is paying for multi-year continuity, not just a clean transition. For key managers like a GM, COO, or head of sales, total deferred retention bonuses often land between 20%–80% of annual base salary. In cases where the buyer leans heavily on that person after closing, the total can stretch to 100%–150%. Broader professional staff and supervisors are more likely to get 10%–30% of salary in total multi-year awards, often tiered by seniority.
Here’s what that can look like in practice: in a $5 million enterprise value acquisition, a GM with a $150,000 base salary might receive a $120,000 total deferred bonus. That equals 80% of salary, paid as $40,000 per year across three anniversaries, as long as the employee stays and EBITDA remains within 90% of budget.
Payout timing
Deferred plans often run 2–5 years after closing, with three years being a common choice. The simplest setup is annual vesting with annual cash payouts. For example, one-third of the total bonus gets paid on each of the first three closing anniversaries.
Some buyers take a different route and use back-loaded or cliff vesting. In that setup, little or nothing vests in year one, and a bigger share - sometimes 50%–70% of the total - gets paid in year two or year three if the employee is still on the job and meets basic performance goals. Payment dates are often tied to fixed calendar timing, such as within 75 days after each December 31 year-end, which gives the company time to confirm financials or EBITDA.
Vesting conditions
The main condition is continued employment on each vesting date. If an employee quits or is fired for cause before a vesting date, unvested amounts are usually lost. Many agreements also allow prorated vesting if the employee is terminated without cause, with payment due within 60 days.
When performance conditions show up, they’re usually set at thresholds that matter but are still within reach. A common example is EBITDA staying within 90%–110% of the pro forma budget. That keeps the plan tied to business results instead of turning it into a bonus that looks good on paper but never gets paid.
Deal fit
This setup works best when the buyer’s plan depends on continuity and growth over several years, not just getting through closing without a mess. That often includes platform roll-ups, hard integrations, and businesses where key customer ties or specialized know-how live with middle management instead of the departing owner.
It can also fit well when the buyer is a financial sponsor or search fund with a multi-year growth plan. The tradeoff is pretty clear:
- More admin work
- More room for disputes over metrics
- More risk that employees feel stuck if they’re unhappy but don’t want to leave unvested money behind
That tradeoff tends to matter most when deciding between simple cash bonuses, staged payouts, and milestone-linked plans.
Get a Quality of Earnings analysis you can trust
Amounts, Terms, and Tradeoffs Compared
These four bonus structures solve different problems.
A closing bonus is about speed. A staged stay bonus helps with handoff and continuity. A milestone bonus ties pay to results. And a deferred plan is built for keeping key people in place over several years. In practice, the right pick usually comes down to deal size, available cash, and how long the buyer needs the employee to stay.
The table below pulls those tradeoffs into one view: size, timing, stay period, and what happens if the employee leaves.
| Structure | Typical % of Base Salary | USD Example ($120K Base) | Payment Schedule | Required Stay | Forfeiture Rule | Best-Fit Context |
|---|---|---|---|---|---|---|
| Simple Cash Closing Bonus | 10%–30% (can reach 50% in small deals) | $12,000–$36,000 | Lump sum at closing or within 30 days | No post-close service requirement | Forfeit if not employed at close or terminated for cause before close | Main Street; speed-driven deals |
| Cash Stay Bonus (Staged Tranches) | 20%–40% | $24,000–$48,000 | 50/25/25 at close, 6 months, and 12 months | 6–18 months | Unpaid tranches forfeited on resignation or for-cause termination; remaining tranches often accelerate on termination without cause | Main Street and smaller lower-middle-market |
| Milestone-Based Retention Bonus | 30%–60% | $36,000–$72,000 | Paid when a defined revenue, EBITDA, or integration target is met | 12–36 months | Forfeit on voluntary exit or for-cause termination before milestone is certified; earned amounts may accelerate on termination without cause | Lower-middle-market; senior leaders |
| Deferred Multi-Year Retention Plan | 50%–100% of base salary | $60,000–$120,000 per year ($180,000–$360,000 total over 3 years) | Annual vesting over 3–5 years, sometimes with a larger final payment | 3–5 years | Unvested amounts forfeited on resignation or for-cause termination; double-trigger acceleration common | Lower-middle-market; senior executives |
Who pays matters too. If the seller funds the bonus, the money comes out of sale proceeds, which cuts the seller’s net. If the buyer funds it, the bonus becomes a post-close operating expense. That keeps the seller’s gross proceeds intact, but it also has to work with the buyer’s cash flow and any lender rules. A split approach is common: the seller covers the closing bonus, while the buyer handles later tranches or milestone payments.
In SBA-backed Main Street deals, these same structures often shift a bit. SBA 7(a) loan terms limit earnouts enough that buyers often use retention bonuses instead. A common setup is a modest closing bonus of $10,000–$25,000 per key employee, paired with a 12-month stay bonus and a simple customer-retention milestone. Framed as compensation, that setup tends to fit SBA deals better than an earnout.
One last term matters a lot: acceleration after termination without cause or resignation for good reason. Many agreements call for immediate payment of unpaid tranches, or at least a pro rata share, in those cases. Milestone and deferred plans may also include double-trigger acceleration. That means a change of control, plus a qualifying termination, must happen before unvested amounts pay out right away.
Pros and Cons of Each Structure
The four structures mainly differ in when cash is paid, how well they keep people in place, and how much work they create to manage. In plain English: use the lightest setup that still covers the buyer’s post-close risk.
Here’s how the four options stack up on burden and retention strength:
| Structure | Pros | Cons | Admin Burden | Retention Strength |
|---|---|---|---|---|
| Simple Cash Closing Bonus | Cash now for the employee; fast to negotiate; easy for all parties to understand | Weakest post-close retention; employee has little financial reason to stay after payment | Low | Low to moderate |
| Cash Stay Bonus (Staged Tranches) | Balances near-term cash with continued commitment; reduces risk of losing people right after closing | Requires payroll tracking across multiple dates; employees may exit after the final tranche | Moderate | Moderate to high |
| Milestone-Based Retention Bonus | Buyer only pays when real value is delivered; strong alignment with integration goals | Harder to define and enforce; disputes can arise if milestones are ambiguous or feel unattainable | Moderate to high | High if milestones are well designed |
| Deferred Multi-Year Retention Plan | Strongest long-term alignment; best for critical leaders; meaningful financial reason to stay for years | Greatest post-close cash flow strain; highest legal and tax compliance issues; can frustrate employees who need cash sooner | High | High |
A Simple Cash Closing Bonus makes sense when the main goal is keeping people engaged through signing and closing, not tying them down for years after the deal. It’s easy to run and light on paperwork. The catch is simple: once the check clears, the employee’s financial reason to stay is gone.
Cash Stay Bonuses give employees clear near-term upside while still creating a set of stay-or-go moments that support the post-close handoff. That can work well in practice because it spreads the incentive across time instead of putting it all up front. The downside is the extra payroll tracking and paperwork, which can pile up fast when the buyer is managing similar agreements across a group.
Milestone-based plans and deferred plans tend to do the best job of keeping people in place, but they also bring the most friction. They need careful drafting, especially around termination terms, clawback rules, and possible tax and legal compliance issues if compensation is pushed out for too long.
Conclusion
Across these four structures, the choice usually comes down to when cash gets paid, how long the person needs to stay, and how much performance risk the buyer is taking on.
In Main Street acquisitions, usually deals under $5 million in enterprise value, simple cash-at-close bonuses and one- or two-tranche stay bonuses are often the best fit. They’re easy to explain, fast to document, and can be paid from closing proceeds or cash flow. For a key operator in a small business, the point is simple: give them a clear, near-term reason to stay through the transition.
Lower-middle-market deals work differently. If a buyer is taking over a multi-location business or another platform with more moving parts, management execution after close can have a major impact on results. In that setting, milestone-based payouts and deferred multi-year plans often make more sense. Short stay bonuses help with the handoff. Milestone payments tie compensation to performance. Deferred pay supports continuity over multiple years.
The sizing should match the role. The term should match the integration risk. And the vesting should match the result the buyer wants to secure. When those pieces line up, they help protect acquisition value.
Related Reading
- Why Team Fit Matters in SMB Acquisitions
- Post-Acquisition Workflow: Key Steps
- Ultimate Guide to Earnouts in SMB Acquisitions
- Tax Treatment of Earnouts in SMB Deals
- How to Retain Key Accounts Post-Acquisition
- Succession Planning for Family-Owned SMBs
- SBA 7(a) Seller Notes: Standby Rules
- Rollover Equity: 7 Key Terms to Negotiate
Sources
- U.S. Small Business Administration — SOP 50 10 Lender and Development Company Loan Programs
- IRS Publication 15-B — Employer's Tax Guide to Fringe Benefits
- IRS — IRC 409A Nonqualified Deferred Compensation Plans
- U.S. Department of Labor — Fair Labor Standards Act
- U.S. Bureau of Labor Statistics — Employee Benefits Survey
FAQs
Who usually pays the retention bonus?
In a business sale, a retention bonus is usually built into the deal to keep key employees in place during the handoff. In many cases, the payout falls between 10% and 30% of annual salary. For top executives, though, packages can go as high as 140%.
The terms are often pretty straightforward. Many plans require the employee to stay on for 12 to 24 months after the deal closes. Some also tie payment to performance, with targets based on revenue or EBITDA.
How do buyers choose the right bonus structure?
Buyers pick a retention bonus structure based on three things: which employees they need to keep, what they want the business to do after closing, and how long continuity needs to last.
In Main Street and lower-middle-market deals, retention bonuses often fall between 10% and 30% of annual salary. Some employees may get more, especially key leaders and executives.
Common terms usually include:
- Time-based vesting over 12 to 24 months
- Performance-based vesting tied to specific metrics
- Payouts made as either lump sums or installments
What if the employee leaves early?
If an employee leaves before meeting the retention period or misses the performance terms, they usually lose some or all of the bonus. In most cases, these agreements are tied to a 12- to 24-month commitment after the deal closes. They can also depend on milestones like revenue growth or earnings targets.
Typical bonuses fall between 10% and 30% of annual salary. Executives may get 30% or more.
Sell with advisors who maximize your outcome
From valuation and positioning to closing the deal, we run a competitive process to get you the best terms.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.