License Transfer Rules in SMB Acquisitions
How licenses move in stock vs asset SMB deals, agency timing, lender risk, and a buyer's checklist to avoid operational gaps.
 Samson JagorasPrincipal & CEO/CIOSeptember 15, 2026
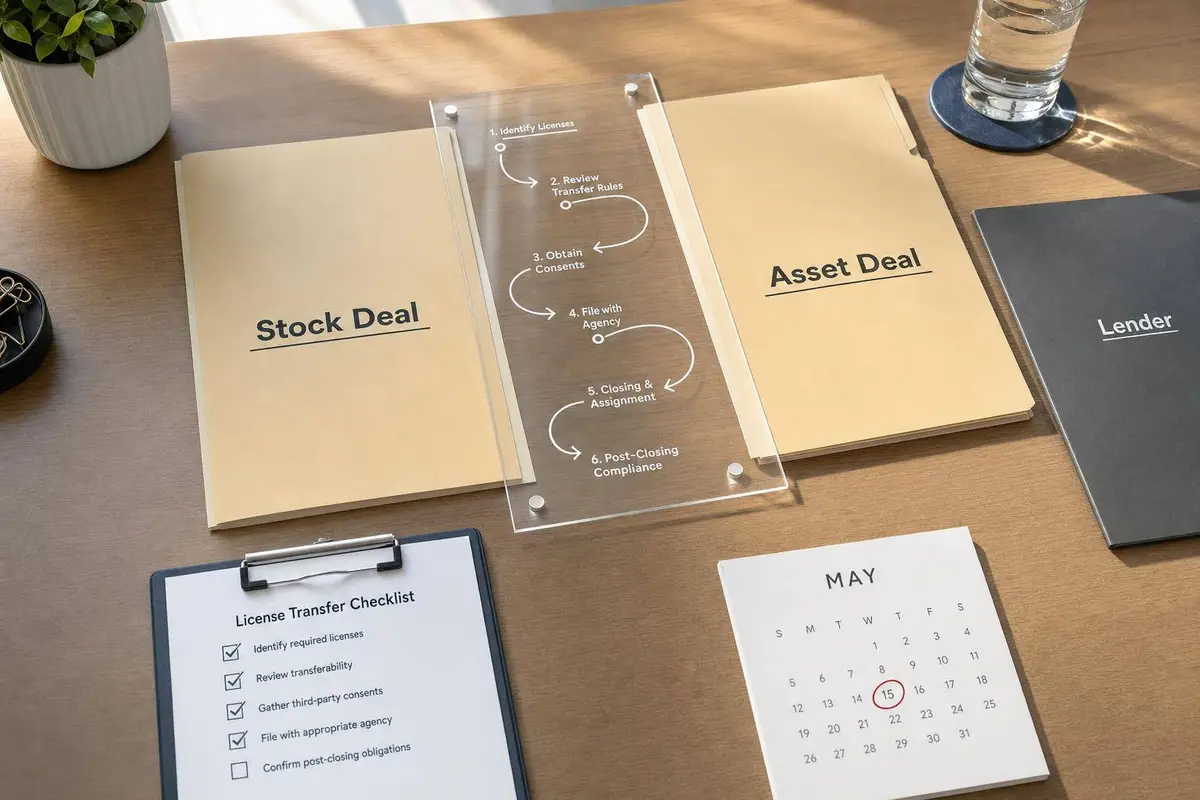
Buying the business does not mean you can legally run it on day one. In many SMB deals, one missing permit, one named-person license, or one slow agency review can delay closing, stop funding, or leave you unable to open after you pay.
Here’s the short version:
- In a stock sale, the entity stays alive, so many licenses stay with it - but change-of-control rules, owner disclosures, and named-manager rules can still trigger filings or approval.
- In an asset sale, most licenses do not move over by default. The buyer often has to file as a new applicant.
- Review times can be long: many permits take 30 to 120 days, liquor approvals can take 3 to 6 months, and some local approval paths can stretch to 225 days.
- Lenders, including SBA 7(a) lenders, often want proof that needed licenses will be in place at closing.
- If timing is tight, buyers often use long-stop dates, seller help covenants, TSAs, escrow holdbacks, and license-specific closing conditions.
If I were buying a small business, I’d focus on five things first:
- List every license and permit
- Check who or what holds each one
- Confirm if it stays, transfers, or must be reissued
- Match agency timing to the closing calendar
- Put that risk into the purchase agreement

Stock Sale vs. Asset Sale: License Transfer Rules in SMB Acquisitions
Expert Insights in SMB M&A - Eric Pacifici - Partner @ SMB Law Group
sbb-itb-a3ef7c1
Quick comparison
| Issue | Stock sale | Asset sale |
|---|---|---|
| Who owns the licensed entity after close | Same entity | New buyer entity |
| What usually happens to licenses | Often stay with entity | Often need new filing or approval |
| Main risk | Change-of-control rules; named person leaves | Buyer cannot use seller’s licenses |
| Timing risk | Notice or consent may be needed before close | Reissue or transfer review may delay start of business |
| Deal impact | Closing may wait on agency sign-off | Buyer may not be able to operate right after close |
Bottom line: I’d treat licenses as a closing item, not post-close cleanup. The deal date should follow agency timing, lender timing, and license status - not the other way around.
Problem 1: Deal structure changes the license outcome
Deal structure shapes what happens to licenses after a sale. It can decide whether a license stays in place, needs notice, or has to be filed again from scratch. The same business can face very different approval paths depending on whether the deal is structured as a stock sale or an asset sale.
Stock sale: continuity helps, but change-of-control rules still apply
In a stock sale, the buyer acquires the seller's equity - stock or membership interests - so the legal entity itself stays the same. Because that entity survives, many licenses remain with it after closing.
That said, survival of the entity doesn't give you a free pass. A big ownership change can still trigger notice, consent, or updated disclosures. Many licensing agencies treat a major shift in ownership as a reportable event, or one that needs approval, even when the licensed entity continues to exist. Depending on the industry, regulators may require advance written notice before closing, prior agency consent, updated ownership disclosures, or background checks for new owners and officers.
So yes, continuity helps. But it doesn't wipe out approval rules.
Stock deals also come with one risk that's easy to miss: named-person dependency. If a license depends on a named qualifying contractor, supervising pharmacist, or responsible liquor manager, and that person leaves at closing or soon after, the license can be at risk even though the entity never changed. That's why buyers in a stock deal need a full change-of-control review for every material license. They can't just assume the entity's survival solves the problem.
Asset sale: most licenses do not transfer automatically
In an asset sale, the buyer acquires selected assets - equipment, inventory, customer contracts, and real estate - but not the seller's legal entity. And that's where things get tricky. Regulators usually treat licenses as permissions tied to a specific legal entity or person, not as business assets that move over with the sale.
Unless a statute clearly allows a transfer from seller to buyer, the buyer is usually treated as a new applicant. In plain English, that often means new applications, inspections, fingerprints, background checks, local approvals, and agency review periods that can stretch from 30 to 120 days. For liquor licenses in some states, that wait can run 3 to 6 months. During that gap, the buyer may not be able to operate at all.
For example, federal TTB permits for alcohol production are non-transferable no matter how the deal is structured, so the successor must qualify as a new applicant whether the transaction is an asset sale or a stock sale.
That turns license timing into a closing issue, not some small post-close paperwork item.
Asset sale vs. stock sale: license continuity comparison
| Feature | Stock Sale | Asset Sale |
|---|---|---|
| Entity continuity | Legal entity survives; licenses generally stay in place | New entity; seller's entity retains its licenses |
| Transferability | Higher; continuity is the default | Lower; most licenses do not transfer automatically |
| Agency consent risk | Triggered by change-of-control or ownership disclosure rules | Usually requires full reapplication or formal transfer approval |
| Timing risk | May require pre-close consent or post-close notice filings | Often requires full approval before the buyer can legally operate |
Even if the deal structure looks right on paper, state and local agencies can still slow down closing - or stop it cold.
Problem 2: State and local agency review can delay or block closing
Once the price and deal structure are set, it’s easy to think the hard part is done. It’s not. In a lot of deals, the closing date is driven less by the buyer and seller and more by agency calendars, filing rules, inspection schedules, and notice periods. That’s why agency review needs to be mapped before anyone commits to a closing date.
How agencies handle ownership changes and transfer requests
Even if a license can transfer, the agency still decides how and when that happens. A simple way to map the approval path is to sort each license into three buckets:
- Transferable with notice: the buyer closes first, then files the required notice.
- Transferable only with prior approval: the agency has to approve before the buyer can operate, so the agency’s review timeline controls closing.
- Nontransferable: the buyer has to apply for a new license.
The timing can vary a lot by state. Some health and alcohol licenses need a filing or approval before closing. Others require a brand-new license, which can take weeks or months. If the path to approval isn’t clear, that license should be treated as a closing risk, not something to deal with after the sale.
Common filing and review bottlenecks before close
Once you know the filing path, the next problem is delay inside the review process. Agencies usually won’t start a real review until they have every required document. That means incomplete applications, missing ownership disclosures, unsigned forms, or background-check delays can stop the process cold. And if the buyer has a layered ownership structure or there were recent management changes, the disclosure load often gets heavier.
Some permits also turn into a boots-on-the-ground issue. Health, fire, and occupancy approvals often depend on an on-site inspection before the agency will move forward. In New York City, the comptroller's office found that it takes business owners an average of 225 days to obtain needed approvals to open, with many receiving minimal feedback while they wait. If a buyer learns late in the deal that an inspection is required but hasn’t even been scheduled, that’s not just a paperwork snag. It can push closing off track.
Another common holdup is more avoidable: filing with the wrong agency unit. Many regulators split transfer requests, new applications, and change-of-control notices across different divisions. It sounds minor, but it can burn weeks. Smart buyers treat agency outreach as part of diligence, not a cleanup job after the fact. The filing schedule should be built around those review steps from the start.
Ready to Make Your Next Move?
Whether you're buying, selling, or investing — Clearly Acquired gives you the tools, data, and support to close with confidence.
Problem 3: License timing risk can reset the closing date
A purchase agreement might aim for a 45-day close. But in regulated deals, licensing often has the final say.
If a required transfer or reissue takes longer than planned, the agency's review calendar - not the LOI - sets the actual closing date. And once that happens, the deal timeline stops being a simple schedule and starts turning into a risk item. At that point, the buyer needs to bake licensing into both diligence and the purchase terms.
Where timing risk hits the deal hardest
Funding is usually the first domino to fall. When approvals drag, funding gets held up too. Bank and SBA commitments often expire within 30–90 days, which can force re-underwriting, updated financials, or added fees.
Day-to-day operations don't pause just because paperwork is stuck. Payroll still needs to run. Suppliers still need to ship. Big customers may refuse to activate accounts or release funds unless the business holds the needed licenses.
Timing risk tends to hit regulated businesses the hardest, especially:
- restaurants
- healthcare
- childcare
- transportation
- fintech
- contractors
| Industry | Typical License Review Period | Primary Risk if Delayed |
|---|---|---|
| Restaurants (with liquor) | 45–90 days | Cannot sell alcohol; revenue loss from day one |
| Healthcare / home health | 90+ days | Cannot bill insurers or government programs |
| Childcare / transportation | 60–90 days | Facility inspections required; operations halted |
| Fintech / mortgage | 30–90 days (some states 90+ days) | Cannot originate or service; regulatory exposure |
| General contractor | 30–60 days | Cannot legally perform work under new entity |
Delayed closing can also wear down seller cooperation. And the longer a deal sits, the more likely it is that price talks reopen because new financials, market shifts, or both come into play.
What buyers can do when approvals will not be ready by closing
The simplest move is to build more time into the deal from the start. In regulated industries, that often means negotiating a 60–90 day signing-to-closing period instead of the usual 30–45 days.
It also helps to set a clear long-stop date. That's the outside date when either party can walk away if the named license approvals still haven't come through. For SMB deals with meaningful regulatory exposure, long-stop dates are often set 3–9 months from signing, based on agency timing plus some buffer room.
If approvals plainly won't arrive before closing, buyers usually turn to seller cooperation covenants and transition services agreements (TSAs).
A seller cooperation covenant requires the seller to help with the process - filing documents, signing forms, and dealing with agencies as needed. A TSA can let the seller keep operating under current licenses for a limited period while the buyer runs the business day to day. One common example is a seller staying on as the named liquor license holder during the transfer period. If that route is used, the parties need clear terms around revenue sharing, insurance, and compliance.
That said, these setups need careful drafting. Agency rules matter, and SBA lenders often look closely at post-close operating structures.
On the money side, escrow and deferred consideration are common ways to tie payment to licensing results. Part of the purchase price - often around $150,000 to $500,000, depending on deal size and how central the license is - is held in escrow and released only if a named license is approved by a set date.
If approval is denied or delayed in a serious way, that escrow can go back to the buyer or be used in a revised pricing deal. Buyers also often ask for targeted indemnities. Those can cover losses tied to undisclosed compliance problems or seller misstatements that lead an agency to delay or reject a transfer, up to an agreed cap.
These tools help assign timing, payment, and compliance risk before closing. Which is exactly why buyers need to confirm the transfer path before the closing date gets locked in.
Solution: A buyer's playbook to confirm transfer paths before close
Licensing risk has to be handled before close. In regulated SMB deals, buyers that do this well treat licensing as a core diligence workstream, not something to sort out after the ink dries.
The playbook is pretty simple: do a license-by-license review before the closing date is locked in.
Build a complete license and permit inventory
Start by mapping every regulatory touchpoint the business has: federal, state, county, city, site-level, and professional. That includes liquor licenses, health department permits, zoning approvals, contractor licenses, environmental permits, and any credential tied to a named person, such as a pharmacist-in-charge, designated broker, or medical director.
For each item, log the key details in a structured spreadsheet:
- Issuing agency
- License number
- Legal holder
- Status
- Expiration date
- Any fines, consent orders, or pending investigations
- Whether the license is entity-based or personal
- Whether it is location-specific or enterprise-wide
- Whether operations depend on that person staying after close
Don’t just use the seller’s summary list. Pull the actual certificates and check standing directly with the issuing agencies.
Pay close attention to legacy permits, site-specific environmental permits, and auto-renewing local licenses.
That inventory becomes the base for every later filing, consent, and closing condition.
Confirm the transfer path with documents and agency guidance
Next, record the exact filing path and any pre-close requirement for each license. For every item, review the license certificate, the agency’s instructions, and the underlying statutes and regulations for assignment, change-of-control, or ownership-change language.
Then cross-check the draft purchase agreement for clauses that could trigger a notice requirement or limit the transfer. If the rules are murky, contact the regulator directly - alcohol beverage control boards, state health departments, or childcare agencies - and document who you spoke with, the date, and what they confirmed.
Put the results into a license transfer matrix. Use one row per license, with columns for the current holder, proposed post-close holder, deal structure, required action, responsible party, estimated timeline, and risk rating.
This matrix becomes the main reference point for licensing calls during the deal. Once the path is clear, the deal terms should line up with the approval timeline.
Turn diligence findings into closing terms and a filing tracker
Use the transfer matrix to shape the purchase agreement. Licensing risk should decide whether each item is a condition precedent, covenant, holdback, or outside-date trigger.
High-risk licenses should show up as conditions precedent. In plain English, the deal does not close until the buyer has approval, or written assurance of approval, for those licenses. Medium-risk items fit better as covenants, with both sides required to cooperate on filings and agency communications through close.
If timing is uncertain, tie part of the purchase price to licensing outcomes through escrow or holdback arrangements. Add an outside date so either party has a clear way out if critical approvals do not arrive. Representations and warranties should confirm that all listed licenses are valid, in good standing, and free of undisclosed violations.
Run a dated filing tracker alongside the closing calendar. It should list each regulatory action, owner, prerequisite, fee, filing date, and expected approval date based on agency guidance. Review it during weekly deal calls and line it up with financing milestones.
Conclusion: Confirm license transfer paths before you set the closing date
After deal structure, agency review, and timing risk, the big point is simple: licenses and permits decide whether the buyer can legally operate on day one.
Here’s the rule to keep in mind: owning the company does not automatically transfer the right to run it. A sale can shift control without shifting the license holder.
Timing matters a lot here. Buyers who spot licensing limits at or before the LOI stage can use that information to shape the deal structure, outside dates, and capital plan. Buyers who find out in the last few weeks before closing that a license can’t be transferred have far fewer moves left - whether it’s an asset sale or a stock sale. Lenders are watching this too. SBA 7(a) loan terms vs. other financing options often want proof that all required licenses will be in place at closing.
So the job is pretty straightforward:
- Inventory every required license
- Check transfer rules with the issuing agencies
- Build approval timing into closing conditions and the filing schedule
- Treat agency timelines as fixed inputs
In SMB acquisitions, the closing date should follow license approval, not come before it.
FAQs
Which licenses can block closing?
Licenses and permits can stall a deal when they don't transfer on their own.
In a stock sale, the legal entity usually stays the same. That means licenses may stay in place too.
In an asset sale, it's often a different story. Buyers may need to reapply for licenses or get approval from the issuing agency. That can slow down closing or leave a gap where the business can't operate as planned.
To cut this risk, buyers usually check permits early, confirm transfer rules with the agencies that issued them, and figure out whether any qualifying individuals are required.
Can I operate while a license transfer is pending?
It depends on how the deal is set up and what the license allows.
In an asset sale, licenses and permits usually do not transfer on their own. The buyer may need to file new applications or get approval from the agency before the business can keep operating.
In a stock sale, the legal entity stays the same. Because of that, the licenses may stay with the company.
Buyers should check the transfer rules early. That step can save a lot of trouble later. If a license is tied to one person and can't be transferred, the business may not be able to operate legally after closing.
When should I start license transfer diligence?
Start during due diligence, ideally 3 to 6 months before closing. License and permit rules can shape the deal structure, affect timing, and even determine whether the acquisition can close on schedule.
Buyers should check whether licenses transfer in a stock sale or require reapplication in an asset sale. Then they need to confirm that process with the right state or local agencies. Missing approvals can delay closing or interrupt operations.
Related Reading
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.