SBA 7(a) Personal Guarantee Requirements for Buyers
Who must sign SBA 7(a) guarantees, what liabilities and collateral apply, and how to secure releases before closing.
 Samson JagorasPrincipal & CEO/CIOOctober 25, 2026
Get matched with the right lender for your business
Compare offers from our vetted network. Pre-qualify in minutes — no impact to your credit.
If you own 20% or more of the business - directly or indirectly - you generally must personally guarantee an SBA 7(a) acquisition loan in full. Before signing, I’d get the lender’s guarantor list and liability terms in writing. The SBA guarantee protects the lender, not you.
Here’s what I’d check before closing:
- Who must sign: Ownership through entities, trusts, and certain family holdings can affect the rules. Lenders may also require guarantees from owners below 20% or from nonowners.
- What I could owe: Form 148 generally covers the full debt; Form 148L limits liability as stated. Interest and collection costs may also apply.
- Which assets are pledged: Personal liability and collateral are separate. A spouse’s signature may provide lien consent without creating full repayment liability.
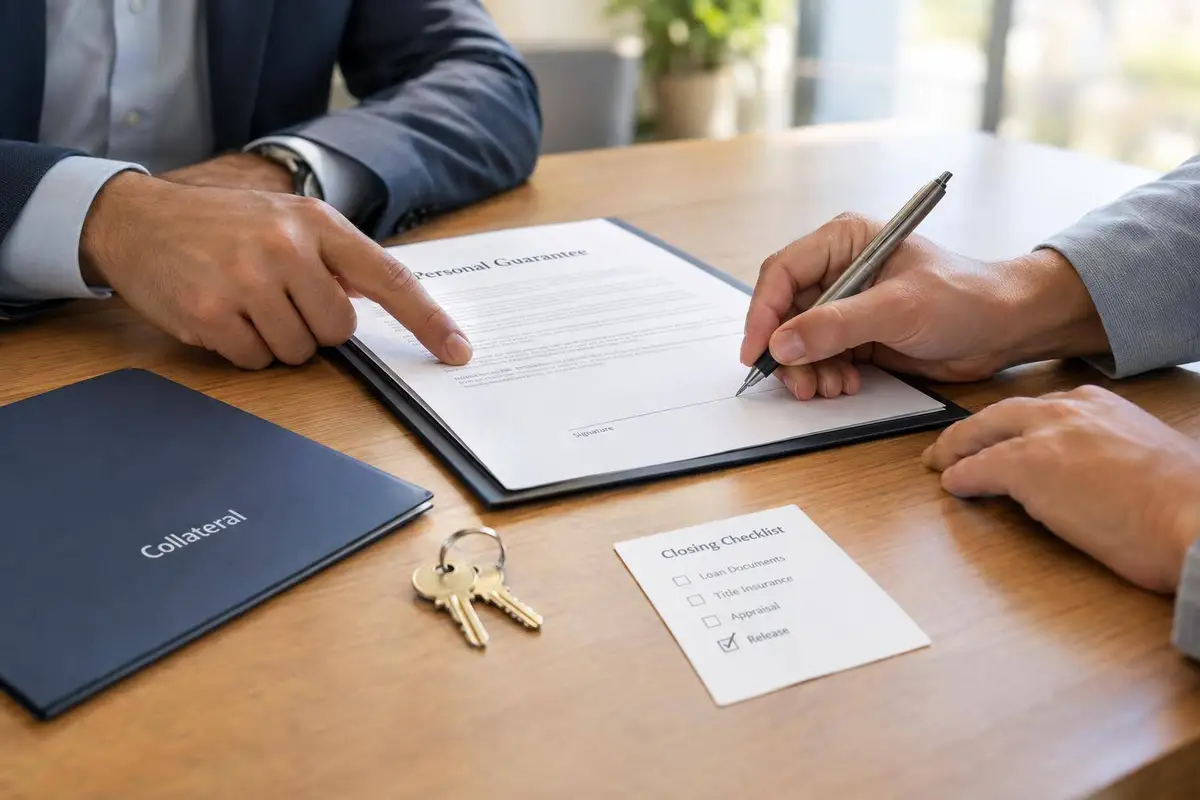
- How liability ends: Selling an ownership stake does not automatically release a guarantee. I’d require written release terms and have counsel review the closing documents.
<u>The key distinction:</u> who must guarantee, what they owe, and which assets secure the loan are three separate questions.

SBA 7(a) Personal Guarantees: Who Signs, What You Owe, and Collateral
Do You Need to Provide a Personal Guarantee for SBA Loans?

sbb-itb-a3ef7c1
When Lenders Require Additional Guarantees
After applying the 20% rule, lenders may still require guarantees when using SBA 7(a) loans for business purchases based on a person’s control, role, or repayment support.
Ask the lender to identify each signer as an SBA-required guarantor or a supplemental lender-required guarantor. Lenders cannot waive a mandatory SBA guarantee. They may, however, require additional guarantees from noncontrolling parties when SBA rules allow it. Get that distinction in the lender’s written guarantor list.
Guarantees from Minority Owners and Key Individuals
Owning less than 20% does not automatically exempt someone from a guarantee. Subject to SBA rules and lender policy, minority owners, operating partners, managers, and nonowners may need to provide full or limited guarantees if their control, cash support, or business role affects repayment. Management authority, veto rights, and equity-injection funding can also trigger a guarantee.
Discuss guarantee requirements during preliminary lender screening. Before signing final loan or acquisition documents, get written confirmation of who must sign, why, and how much liability each person takes on. Check whether the guarantee covers principal, interest, fees, and collection costs. Also confirm any cap, time limit, or conditions for release.
If a supplemental guarantee seems out of step with someone’s role, ask which credit concern it addresses. Could a reserve, replacement-management plan, additional collateral, or narrowly limited guarantee address that concern instead? These options address lender credit concerns; they do not replace required SBA guarantees.
Ownership and Guarantor Checklist
Keep one dated ownership and guarantor file. Update it whenever ownership, control, or equity funding changes. Include:
- Complete capitalization table: Cover the acquisition entity, holding companies, and operating company. Keep the ownership chart and details of any spouse or family interests that affect guarantor status.
- Supporting documents: Include trust instruments, entity formation records, operating agreements, bylaws, subscription agreements, and side letters that show voting, veto, management, and signing rights.
- Guarantor schedule: List every proposed mandatory and supplemental guarantor. Record each person’s ownership, business role, the lender’s written basis for requiring the guarantee, proposed guarantee form, full or limited liability, any cap or duration, and release conditions.
- Lender confirmation: Get written acceptance of the ownership calculations and guarantor list, including any decision not to require a minority owner’s guarantee. Collect requested personal financial statements, and have counsel review the proposed terms before signing.
Guarantee Forms and Loan Terms
Once you know who must guarantee the loan, check the exact form and liability terms against the final authorization before closing.
SBA Form 148, Form 148L, and Permitted Alternatives
Use SBA Form 148 for a full guarantee and Form 148L (Unconditional Limited Guarantee) when the authorization allows a limited guarantee. Lenders can use SBA forms or their own guarantee agreements, but the terms must match the authorization and current SBA requirements.
For Form 148L, check the selected limitation. Only one option is permitted per guarantor. With a balance-reduction limitation, the guarantee can remain in force until the loan balance reaches the stated amount. Default can delay or prevent release.
Compare the final guarantee with the loan approval, promissory note, security agreement, mortgage or deed of trust, and final settlement statement. Names, debt amounts, collateral, and limitation terms should all match.
Those limitation terms set how much the lender can recover if the borrower defaults.
Repayment Liability and Enforcement
An unlimited guarantor may owe the unpaid guaranteed obligations: principal, accrued interest, permitted attorneys’ fees, and collection costs. A limited guarantor owes only what the signed limitation covers, but a stated cap may not cover every additional charge.
If liability is joint and several, the lender can pursue any one guarantor for the full covered amount. Private loss-sharing agreements among owners do not limit the lender’s rights unless the lender expressly agrees.
Read the default, demand, notice, and waiver provisions together. Enforcement generally follows a default or another default event listed in the loan documents. Don’t assume the lender must sell the collateral before pursuing you. Those rights depend on the documents and applicable law.
Ownership Changes and Guarantee Releases
A guarantee does not end automatically when ownership changes after closing - even if you sell your interest or fall below 20% ownership. A partial loan payoff does not automatically end it either.
Make a departing owner’s written release a closing condition, with the effective date and released obligations clearly stated. Obtain lender consent and confirm any SBA release requirement. For a refinance or modification, check whether the existing guarantee continues or new documents replace it.
After full payoff, request written confirmation that the debt and guarantee are satisfied, along with any applicable lien releases and UCC termination filings.
Personal liability is separate from the collateral the lender can also reach.
Personal Guarantees vs. Collateral
Once you know who must sign, separate personal liability from the assets pledged to the lender. Collateral does not change who must guarantee the loan. It determines which assets secure repayment if the borrower defaults.
Personal Liability vs. Pledged Assets
A guarantee makes you personally responsible for repayment. Collateral gives the lender rights in specific property. A buyer can face both on the same SBA 7(a) loan.
| Feature | Personal guarantee | Collateral | Buyer exposure |
|---|---|---|---|
| What it does | Contractual promise to repay the debt | Security interest or lien in specified property | Separate remedies that may apply together |
| Documents | SBA Form 148, Form 148L, or lender-approved equivalent | Security agreement, mortgage, deed of trust, UCC filing, or pledge | A guarantee does not itself pledge assets |
| Affected assets | Nonexempt assets may be reached after judgment | Property covered by the security documents | A guarantee does not itself create a home lien |
| If the borrower defaults | Payment demand and judgment enforcement | Foreclosure, repossession, or collateral sale | A deficiency may remain collectible |
This distinction matters when selling the collateral does not cover the debt. Request a written collateral schedule that lists each asset, its owner, value, lien position, perfection method, and release condition.
Recovery Rights When Collateral Falls Short
When collateral sale proceeds do not cover the debt, the shortfall is called a deficiency. The lender may still collect it under an enforceable guarantee. Ask counsel whether the documents allow the lender to demand payment before selling the collateral. Also confirm how sale proceeds and collection costs affect what you still owe.
An SBA payment to the lender does not forgive your debt. Ask how collateral proceeds, SBA payments, and later recoveries will be credited - and what the lender can still collect from the borrower and guarantors.
Spouse Signatures and Jointly Owned Property
A spouse may need to sign because of ownership thresholds or lien consent - not simply because you’re married. A spouse who owns 20% or more generally must provide an unlimited guarantee. The combined-ownership rule also applies when both spouses own at least 5% and together own 20% or more. A non-owner spouse may instead sign only to make jointly owned property available as collateral.
Check whether each signature creates full repayment liability, lien-only consent, or both. The operative language - not the document title - controls. A spouse’s signature may give the lender access to collateral without creating full repayment liability.
Conclusion: Confirm Your Exposure Before Closing
Once you know who must guarantee the loan, check the closing package to make sure the final documents match the approval.
The 20% rule sets a minimum guarantee threshold. Ownership below 20% does not eliminate exposure. To understand your actual exposure, review ownership, lender requirements, guarantee terms, and collateral documents together.
Use the final authorization for one last check before anyone signs.
Final Guarantee and Collateral Checklist
- Confirm who signs: Verify all required guarantors, their authority to sign, and the required personal financial statements. Finalize the ownership chart and make sure it matches the guarantor list.
- Confirm the form: Obtain the signed SBA Form 148, Form 148L, or approved equivalent. Read each guarantee alongside the note, SBA authorization, and security documents. Check any limits on liability.
- Confirm the collateral: Verify pledged assets, lien priorities, and any required spouse signatures.
- Confirm release terms: Get release, payoff, and transfer conditions in writing.
Coordinate Lender, Advisor, and Legal Reviews
Have your attorney review liability, liens, waivers, and release language before anyone signs. Get tax advice if entity, trust, or family arrangements are involved. Before signing, ask the lender to correct any mismatches in names, ownership percentages, loan amounts, collateral descriptions, or guarantee limits.
Keep the signed authorization, guarantee forms, collateral schedules, and release documents together in one closing file.
FAQs
How is my indirect ownership calculated for the 20% rule?
The information provided doesn’t explain how indirect ownership is calculated. It states that individuals or entities owning 20% or more of the purchasing entity must provide an unlimited personal guarantee. Lenders may also require guarantees from key executives or managers.
A guarantee creates personal liability, while collateral means pledging specific assets. SBA Form 413 documents your personal assets and liabilities.
Can I negotiate a lender-required guarantee?
For SBA 7(a) acquisitions, owners with a stake of 20% or more must provide an unlimited personal guarantee. This isn’t optional. Lenders may also require guarantees from key executives or managers.
A guarantee makes you personally liable if the business defaults. Collateral, on the other hand, refers to assets pledged to secure the loan.
Required paperwork includes SBA Form 1919 and Form 413. Form 413 is a personal financial statement that must be current within 90 days of closing.
How can I secure a guarantee release before selling my stake?
The information explains the guarantee requirements, but it doesn’t explain how to get released from a guarantee before selling your stake.
For SBA 7(a) acquisitions, anyone who owns 20% or more of the acquiring entity must provide an unlimited personal guarantee. That means they’re personally liable if the business defaults. Lenders may also require guarantees from key executives or managers.
Related Reading
Find the right lender for your business
Whether it's working capital, an SBA loan, or acquisition financing — we'll match you with the right capital partner.
About the author
Principal & CEO/CIO
Samson Jagoras has 15+ years across finance, real estate, and business acquisitions. He began his career as a Futures & Commodities broker and later served as Chief Strategy Officer of an INC 500 marketing and technology firm, helping scale revenue from $1M to over $100M. Today he buys, builds, and advises a portfolio of companies with a focus on M&A, capital allocation, and operational strategy.